The Howey Test: Understanding Securities Regulation in Cryptocurrencies and ICOs
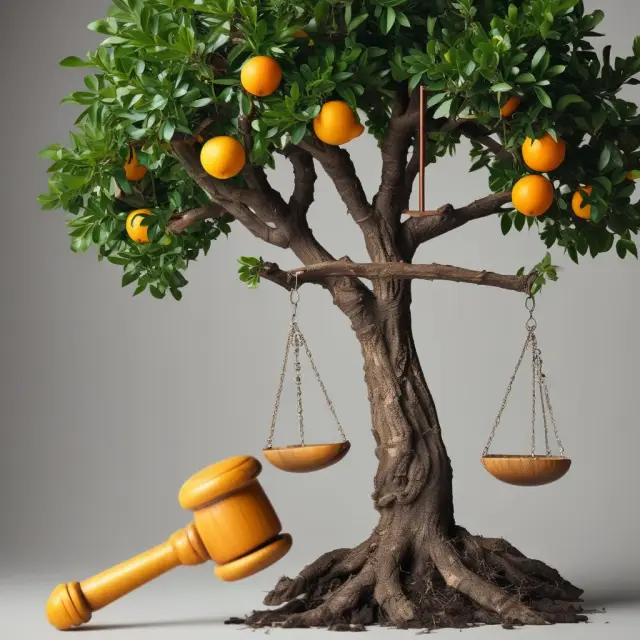
Explore the impact of the Howey Test on securities regulation in cryptocurrencies and ICOs. Learn about its origins, four criteria, and implications.
Background of the Howey Test
The Securities Act of 1933 and the Securities Exchange Act of 1934 were passed in response to the stock market crash of 1929, which marked the beginning of the Great Depression. The U.S. government aimed to protect investors from fraudulent securities offerings through registration requirements and the application of securities laws. In determining what constitutes a “security,” the U.S. Supreme Court established the Howey Test in SEC v. W.J. Howey Co., in 1946.
The landmark case centered around Florida citrus growers, Howey Company, that sold tracts of land to investors and leased back the land for agricultural production. The investors received revenue shares from the sale of oranges harvested on the property. However, the SEC argued these transactions were not exempt from securities regulations since they met the definition of an “investment contract.”
The Howey Test is composed of four criteria: (1) An investment of money, (2) A common enterprise, (3) With a reasonable expectation of profit, and (4) Derived from the efforts of others. The test determines whether a transaction qualifies as an “investment contract” and, subsequently, falls under federal securities regulations.
The Howey Test has significant implications for modern-day blockchain projects and digital assets, including cryptocurrencies and initial coin offerings (ICOs). As we delve deeper into understanding the Howey Test and its application to these emerging technologies, it’s essential to examine each of its criteria in detail.
(To be continued)
Understanding the intricacies of the Howey Test is crucial for investors, developers, and legal experts involved with blockchain projects and digital assets to navigate regulatory complexities and make informed decisions. The test not only shapes the way we approach fundraising within the industry but also influences how we view and evaluate various projects in the space. Stay tuned as we continue our exploration of the Howey Test’s background, its four criteria, and the implications it has on cryptocurrencies and ICOs.
The Four Criteria of the Howey Test
The Howey Test, derived from SEC v. W.J. Howey Co., is a crucial legal framework for understanding securities regulation and its impact on cryptocurrencies and initial coin offerings (ICOs). This test determines whether a transaction constitutes an investment contract, making it subject to disclosure and registration requirements under U.S. securities laws. To understand this pivotal aspect of blockchain projects, we must first delve into the four criteria that define an investment contract according to the Howey Test.
1. An Investment of Money
Investment contracts are initiated with the “investment of money.” The transfer of capital in exchange for a potential return or profit is the fundamental requirement for securities laws to apply. This investment can take various forms, including cash or other financial instruments like stocks and bonds. In the context of cryptocurrencies and ICOs, the “money” requirement is typically met when participants exchange their fiat currency or digital assets for new tokens.
2. A Common Enterprise
The Howey Test’s second criterion states that investments are made “in a common enterprise.” In simpler terms, this implies that the investors pool their resources and share risks, goals, and profits with one another. The SEC has determined that most ICO projects meet this requirement, as investors receive tokens in exchange for an expectation of future growth in value. By investing together in the project, they contribute to the development and success of the common enterprise.
3. An Expectation of Profit
The third criterion requires a “reasonable expectation of profits.” In order for the SEC to classify something as a security, it must show that investors are seeking to derive their return from the efforts of others involved in the project. For many cryptocurrency projects, this is indeed the case—investors anticipate earning profits from their tokens through various means, such as future price appreciation or staking rewards. The SEC has emphasized this point when considering ICOs and the application of the Howey Test.
4. Efforts of Others
The final criterion is that investors are relying on the “efforts of others.” This concept refers to instances where investors rely primarily on the work of project developers, managers, or other individuals to create value for their investment. In the context of ICOs and cryptocurrencies, this often pertains to the efforts invested in research, development, marketing, and maintaining the underlying network. By entrusting these responsibilities to others, investors accept that the value of their tokens may be significantly influenced by the actions of the team behind the project.
The Howey Test has proved essential for defining securities laws as they apply to new technologies like cryptocurrencies and blockchain projects. Its four criteria serve to ensure that regulatory requirements are met while enabling innovation in the digital asset space. Understanding these principles is crucial for institutional investors, professional investors, and projects seeking to navigate the complex landscape of U.S. securities regulations.
Howey Test and Cryptocurrencies
The U.S. Supreme Court case SEC v. W.J. Howey Co. established the landmark “Howey Test,” which defines an investment contract, and therefore what constitutes a security. The test is crucial for understanding how cryptocurrencies and initial coin offerings (ICOs) are viewed by regulators.
The Howey Test states that an investment contract exists when money is invested in a common enterprise with the expectation of profits derived from others’ efforts. This test was established following the sale of citrus groves by the Howey Company, where buyers invested money in the company and expected to profit from its agricultural expertise. In digital asset markets, the interpretation of the “investment of money,” “common enterprise,” and “expectation of profit” criteria can vary, as the decentralized nature of blockchain projects challenges traditional definitions.
An investment of money is typically straightforward for cryptocurrencies because fiat currencies or other digital assets are exchanged to obtain them. However, the determination of a common enterprise and an expectation of profits from others’ efforts can be more nuanced.
The “common enterprise” test is often met in the context of digital assets since investors pool their resources together, expecting the project’s success to benefit the entire community. Additionally, many cryptocurrencies rely on the efforts of developers, project teams, and miners to create network value, making it more likely that profits are derived from others’ efforts.
The “investment contract” definition was further clarified in 2017 when the SEC declared DAO tokens to be securities due to their dependence on ongoing developer support for success. As a result, most ICOs today are unlikely to be accessible to U.S. investors, as they would need to register with the SEC and comply with disclosure requirements.
Understanding the implications of the Howey Test for cryptocurrencies is essential for both institutional investors and project creators alike. The regulatory landscape is constantly evolving, and staying informed can help ensure a compliant approach to investment activities.
Implications of the Howey Test for Cryptocurrency Projects
The SEC has taken a significant interest in cryptocurrencies and initial coin offerings (ICOs) over the years. To understand the regulatory landscape surrounding these digital assets, it’s important to explore how the Howey Test applies to them.
In the landmark case SEC v. W.J. Howey Co., the Supreme Court established a test for determining investment contracts in 1946. Under the Howey Test, an investment contract is considered an “investment of money” in a “common enterprise” with an expectation of profit derived from the “efforts of others.” This definition has been used as the basis for determining whether digital assets are securities under U.S. law.
The SEC’s interpretation of this test, especially the requirement that investors rely on the efforts of others to generate profits, has had significant implications for cryptocurrency projects. In 2017, the SEC declared that DAO tokens were securities, effectively setting a precedent for future ICOs and digital assets.
Cryptocurrencies such as bitcoin are not considered securities under the Howey Test because they do not require an investment in a common enterprise or an expectation of profits derived from the efforts of others. Instead, these decentralized currencies serve as replacements for fiat money and rely on a distributed network of users rather than central authority for their operation.
However, ICOs and other digital assets can fall under the securities umbrella based on the Howey Test. For instance, if investors are buying tokens to reap profits derived from the efforts of the project team or the community, it may be considered a security. This is why the SEC has warned that many token sales could be subject to registration and disclosure requirements.
The implications of the Howey Test on cryptocurrency projects are far-reaching. Projects seeking to raise capital from U.S. investors need to consider securities compliance as part of their fundraising strategies. In 2018, former SEC Chair Jay Clayton stated that every ICO he’d seen met the definition of a security and would likely be off-limits to U.S. investors without proper registration or exemptions.
These regulations can have unintended consequences for innovation and investment in the cryptocurrency space. However, compliance with securities laws is essential for maintaining investor trust and ensuring fair markets.
As the regulatory landscape continues to evolve, it’s crucial for projects seeking to issue digital assets or tokens to stay informed about how the Howey Test applies to their specific use cases. Consulting with legal experts and following SEC guidance can help navigate these complex issues and ensure a successful fundraising strategy.
The Impact of the Howey Test on Token Sales
The U.S. Securities and Exchange Commission’s (SEC) stance on token sales has been subject to much debate and controversy in recent years. This section will explore how the SEC’s interpretation of investment contracts under the Howey Test has affected the regulatory landscape for token sales, and discuss the implications for both projects seeking funding and potential investors.
Background: SEC’s Regulation of Token Sales
The SEC began its scrutiny of token sales in 2017 with the DAO Report, which outlined that the sale of tokens in exchange for Ether, a cryptocurrency, constituted securities offerings under the Securities Act of 1933 and the Securities Exchange Act of 1934. This ruling effectively classified most token sales as securities offerings subject to SEC registration requirements. Since then, there have been numerous regulatory actions, settlements, and statements from the SEC regarding digital assets.
The Howey Test and Digital Assets
Under the Howey Test, an investment contract exists if there is an investment of money in a common enterprise with a reasonable expectation of profit derived from the efforts of others. The “investment of money” condition is easily met when considering the sale of digital assets since fiat currency or other cryptocurrencies are being exchanged during token sales.
The “common enterprise” requirement can also be met in most cases as investors pool funds to support a project, hoping for a return on their investment. However, it’s the third condition – an expectation of profit derived from the efforts of others – that is the crucial factor in determining if a token sale constitutes a security offering under the Howey Test.
Impact on Token Sales: SEC Enforcement Actions and Statements
The regulatory landscape for token sales has undergone significant changes, with the SEC’s enforcement actions and statements providing important guidance for projects seeking funding. For example, in 2018, the SEC charged two entities involved in ICOs with violating securities laws. The first was Munchee Inc., which sold digital food tokens called MUN as an investment vehicle. The second was CarrierEQ/AirFox Tokens Inc., which raised funds through the sale of AIRFOX tokens to invest in a mobile platform for developing countries.
These actions set a precedent that most token sales are securities offerings, making it difficult for U.S. investors to participate and necessitating compliance with SEC registration requirements. Furthermore, the SEC’s statements have clarified its stance on the regulatory framework for tokens as securities. For instance, former SEC Chair Jay Clayton stated in 2018 that “every ICO I have seen is a securities offering.”
Implications for Projects and Investors
The impact of the Howey Test on token sales has several implications for both projects seeking funding and potential investors:
Projects: Compliance with SEC registration requirements can be expensive and time-consuming. As a result, many projects might choose to focus on non-U.S. investors or consider alternative fundraising methods that do not involve tokens as securities offerings.
Investors: The regulatory landscape creates challenges for U.S. investors who wish to invest in token sales. Many are left to rely on unregistered offerings, which can be riskier due to the lack of disclosure and protections afforded by SEC regulations.
Future Developments
The application of the Howey Test to digital assets is an evolving area, with ongoing legal cases providing important insights into the regulatory landscape for token sales. For example, the Securities Act of 1933 does not apply to non-U.S. offerings, so there has been growing interest in decentralized offerings that comply with this exception. Additionally, some projects are exploring alternative ways to structure their token sales to avoid securities status under the Howey Test, such as utilizing utility tokens or decentralized autonomous organizations (DAOs).
In conclusion, understanding the impact of the Howey Test on token sales is crucial for both investors and projects in the cryptocurrency ecosystem. As regulations continue to evolve, it’s essential to stay informed about regulatory developments and best practices for navigating the complex landscape of digital assets under SEC scrutiny.
Special Considerations of the Howey Test
The Howey Test has significant implications for cryptocurrency projects and investors, as it determines whether digital assets are subject to securities laws. Understanding the test’s limitations and challenges is crucial to navigating this regulatory landscape.
One key consideration lies in the fact that the SEC has not provided definitive guidelines on how the Howey Test applies to decentralized cryptocurrencies like Bitcoin. While Clayton clarified in 2018 that Bitcoin itself does not meet the definition of a security due to its decentralization and lack of need for investment or third-party involvement, the SEC’s stance on other cryptocurrencies remains ambiguous. This ambiguity creates uncertainty surrounding which cryptocurrencies fall under securities regulations.
Another limitation is that the Howey Test was established in 1946, long before the advent of blockchain technology and decentralized finance (DeFi). It may not fully capture the complexities inherent in these new systems, such as token economics, decentralized governance, and network effects. The SEC has recognized this challenge and continues to develop its regulatory approach to digital assets.
Additionally, the Howey Test’s application can be subjective and case-by-case. While it provides a framework for determining if an investment contract exists, it does not offer clear bright lines or definitive answers. Each situation is unique, and regulators must consider various factors when applying the test to digital assets. This inconsistency can lead to uncertainty, which may discourage innovation in the cryptocurrency space.
Despite these challenges, understanding the Howey Test and its implications for cryptocurrencies is essential for both investors and projects seeking to navigate regulatory compliance. As the SEC continues to engage with this evolving landscape, it’s crucial that stakeholders remain informed about regulatory developments and best practices. This knowledge can help mitigate risks associated with potential enforcement actions or registration requirements.
In conclusion, the Howey Test is a vital tool for determining whether an investment contract exists in the context of securities laws. Its application to cryptocurrencies and ICOs raises numerous challenges and considerations, necessitating ongoing dialogue between regulators, industry participants, and investors. As the regulatory landscape continues to evolve, staying informed about the Howey Test’s implications will be essential for anyone involved in digital assets or seeking to invest in this space.
Howey Test FAQs
What is the Howey Test and how does it apply to securities?
The Howey Test, named after SEC v. W.J. Howey Co., is a legal test used by the U.S. Securities and Exchange Commission (SEC) to determine whether an investment contract exists and if a transaction qualifies as a security under the Securities Act of 1933 and the Securities Exchange Act of 1934. According to the Howey Test, for a transaction to qualify as an investment contract, there must be:
- An investment of money
- In a common enterprise
- With the expectation of profits
- Derived from the efforts of others
What qualifies as an “investment of money”?
Under the Howey Test, any transaction that involves the exchange of value for something is considered an investment, whether it’s fiat currency or another digital asset like cryptocurrency.
How does the common enterprise criterion apply to securities?
A common enterprise refers to a situation where investors pool their money together and invest in a joint venture with the expectation that profits will be distributed according to their percentage of ownership. The SEC typically finds that a digital token sale meets this criterion if:
- Investors have no control over the underlying asset or project.
- Success relies on the efforts of others, such as the token issuer and their development team.
- Profits are shared among investors based on ownership percentages
What does it mean for an investment to involve “the expectation of profits”?
The Howey Test requires that investors have a reasonable expectation of earning profits from their investment in order for the transaction to qualify as an investment contract. This expectation can stem from a variety of factors, including potential revenue growth or capital appreciation.
How does the “efforts of others” criterion apply to securities?
The efforts of others refer to when investors rely on the work of others to generate profits. For example, if investors in a token sale believe that the success of the project depends on the ongoing management and development by the issuer or their team, this meets the “efforts of others” criterion.
How does the Howey Test impact cryptocurrencies and ICOs?
The SEC has taken an interest in digital assets like cryptocurrencies and initial coin offerings (ICOs) to determine if they meet the definition of investment contracts and securities under the Howey Test. The SEC views most ICOs as securities due to their reliance on pre-sale investors’ capital and the issuer’s efforts in managing and developing the project.
Why is it important for cryptocurrency projects to understand the Howey Test?
Understanding the Howey Test is crucial for cryptocurrency projects that want to comply with U.S. securities laws and attract U.S. investors. By following the guidelines set forth by the test, these projects can ensure they are operating within regulatory frameworks and avoid potential legal issues.
How does the SEC define a security?
The SEC defines a security as “any note, stock, treasury stock, security future, security based swap, bond, debenture, evidence of indebtedness, certificate of interest or participation in any profit-sharing agreement, collateral trust certificate, preorganization certificate or subscription, investment contract, voting trust certificate, certificate of deposit for a security, fractional undivided interest in oil, gas, or other mineral rights, any put, call, straddle, option, or privilege on a security, certificate of deposit or share in a money market fund or mutual fund, limited partnership interest, and unit contract in a real estate investment trust.”
In summary, the Howey Test is an essential tool for determining if certain transactions qualify as securities under U.S. law. By understanding its criteria and implications, cryptocurrency projects can navigate regulatory frameworks and attract investors while maintaining legal compliance.
History of the Howey Test in Cryptocurrency Regulation
The Howey Test, derived from the 1946 U.S. Supreme Court case SEC v. W.J. Howey Co., is crucial for determining whether a cryptocurrency or digital token offering qualifies as an investment contract and therefore falls under securities regulations. This historical perspective will outline key milestones in how the Howey Test has been applied to digital assets and regulatory developments.
In the seminal case, investors bought orange grove tracts in Florida, with Howey Company handling management, maintenance, and sales. The U.S. Securities and Exchange Commission (SEC) argued that these transactions should be registered as securities due to their investment nature. The court ruled in favor of the SEC, establishing the criteria for an investment contract: money investment, common enterprise, expectation of profit, and efforts of others.
Fast forward to the present day. Digital currencies like Bitcoin, decentralized by design, have been a regulatory challenge due to their lack of central authority. The SEC, however, has taken interest in determining how digital assets fit into securities law. For instance, the 2017 DAO tokens sale was deemed a violation of federal securities law but no action was taken against the issuer; instead, the SEC issued a warning to the industry that ICOs could indeed be classified as securities.
The SEC’s position is that the “investment of money” test is easily met in digital asset sales. The “common enterprise” criterion is also easily satisfied due to shared reliance on project backers for network development and maintenance rather than decentralized community efforts. Ultimately, whether a digital asset qualifies as an investment contract depends significantly on the expectation of profit derived from others’ efforts. For example, investors may depend on project backers for ongoing management or support that impacts token value.
The implications of this test have been far-reaching. In Q1 2018, ICOs raised a staggering $6.9 billion. By comparison, the same period in 2019 saw just $118 million in ICO funds raised—a significant decline. These regulatory developments have forced projects to reconsider their token offerings or explore alternative funding methods.
It’s important to note that these interpretations of the Howey Test are not without controversy. Some argue that decentralized networks and autonomous smart contracts could challenge traditional investment contract concepts, potentially changing the scope of securities regulations. The debate continues as regulatory agencies adapt to the digital asset landscape.
The Future of the Howey Test and Cryptocurrencies
As the cryptocurrency landscape continues to evolve, so does the application of the Howey Test in determining which digital assets are securities subject to SEC regulation. Given that most ICOs have been found to be investment contracts under the Howey Test, it’s crucial for projects and their stakeholders to understand the potential future implications of this regulatory framework.
A recent trend in cryptocurrency regulation involves clarifying the definition of a security and establishing when it applies. In 2019, SEC Chairman Jay Clayton announced that his office would take a more nuanced approach to determining whether tokens are securities based on their intended use cases. This new stance could potentially open the door for some decentralized projects to avoid securities classification and thus the need for registration.
In addition, in March 2019, the SEC released its Strategic Hub for Integrated Technology (SHIFT) initiative to provide regulatory clarity and facilitate innovation within the financial technology sector. The initiative includes a focus on digital assets and distributed ledger technologies, suggesting that the SEC is actively seeking ways to accommodate emerging trends while maintaining regulatory oversight.
Moreover, the SEC’s Division of Corporate Finance has issued several no-action letters (NALs) to provide guidance on the application of securities laws to specific token offerings. For instance, in 2019, Blockstack and TurnKey Jet both received NALs for their respective token sales, which helped clarify that these projects could proceed without registration as long as they adhered to certain conditions.
Despite these positive signs, there are still challenges and uncertainties surrounding the application of the Howey Test in cryptocurrency regulation. For example, the definition of a security has been debated extensively, with some arguing that it should be updated to reflect modern realities. Additionally, the regulatory landscape remains fluid, as the SEC continues to adapt its approach to digital assets and ICOs.
One potential future development could involve the establishment of a clearer framework for token sales, with an emphasis on investor protection and disclosure requirements. This might include streamlined registration processes for compliant offerings or a regulatory sandbox that allows innovative projects to test their concepts in a controlled environment. Such changes would provide greater clarity and predictability for both investors and project teams while maintaining the integrity of securities regulations.
As the cryptocurrency landscape continues to mature, it’s crucial for stakeholders to stay informed about regulatory developments and adapt accordingly. This includes understanding the nuances of the Howey Test and being aware of its potential future implications on token sales and decentralized projects. By doing so, investors can make more informed decisions, and project teams can navigate the evolving regulatory landscape with confidence.
Conclusion: The Importance of Understanding the Howey Test
The Securities Act of 1933 and the Securities Exchange Act of 1934, enacted following the Great Depression, established the framework for the regulation of securities in the United States. A key element in determining whether a transaction qualifies as a security is the Howey Test, named after SEC v. W.J. Howey Co., a landmark U.S. Supreme Court case from 1946. The Howey Test evaluates transactions to determine if they meet the definition of an “investment contract” and thus classify as securities subject to disclosure and registration requirements under the aforementioned acts.
An investment contract exists when there is:
- An investment of money in a common enterprise,
- With the expectation of profits, and
- Derived from the efforts of others.
Understanding the Howey Test is crucial for institutional investors, professional investors, and cryptocurrency projects seeking to navigate the complex regulatory landscape surrounding securities. The application of this test to digital assets like cryptocurrencies and initial coin offerings (ICOs) has significant implications. If a transaction meets the definition of an investment contract, it falls under the jurisdiction of the SEC, and the project must comply with the relevant registration and disclosure requirements.
The Howey Test is particularly relevant to the burgeoning cryptocurrency industry due to its ambiguous nature and potential for evasion of securities regulations. The SEC has taken a cautious stance on determining whether digital assets qualify as investment contracts or not, with many ICOs being classified as securities. Under this classification, most ICOs have become off-limits to U.S. investors.
As the cryptocurrency market evolves and regulatory guidance continues to emerge, staying informed about the application of the Howey Test is essential for any organization or individual involved in blockchain projects and digital assets. Best practices include consulting legal experts for advice on specific cases and keeping up-to-date with SEC statements and enforcement actions related to cryptocurrencies and ICOs.
 Next entry · No. 2,238Understanding the Hodrick-Prescott (HP) Filter: A Powerful Tool for Economic Analysis
See also
-
 No. 4,665
07 Jul 2025
22 min
Understanding Simple Agreements for Future Tokens (SAFT): A Legal Framework for Cryptocurrency Ventures
Business Finance
-
 No. 5,666
27 Sep 2025
18 min
Understanding Weis: The Smallest Unit of Ether on Ethereum Blockchain
Crypto
-
 No. 4,191
29 May 2025
18 min
Understanding Qtum: Combining Bitcoin’s Security with Ethereum’s Flexibility for Businesses
Crypto
-
 No. 3,803
28 Apr 2025
18 min
Understanding Orphan Blocks in Blockchain: Definition, Differences from Stale Blocks, and Impact on Bitcoin Mining
Crypto
-
 No. 3,677
18 Apr 2025
21 min
Understanding On-Chain Governance in Cryptocurrency: Decentralized or Centralized?
Crypto
-
 No. 1,119
30 Jul 2024
18 min
Understanding Double Spending in Cryptocurrencies: Prevention and Attacks
Crypto