Net Premium vs Gross Premium: Meaning, Calculation and How Insurers Are Taxed

Gross premium is what the policyholder pays; net premium strips out expenses or reinsurance. Lloyd's 2025: £57.9bn gross, £43.8bn net written premium.
Gross premium is the full price of an insurance policy: what the policyholder is charged. Net premium is what is left once something is taken out, and what is taken out depends on who is talking. To a life actuary, net premium is the part of the price that pays only for expected claims, with expenses, commissions, taxes and profit stripped out. To a property-casualty insurer's accountant, net written premium is gross written premium minus the premium passed on to reinsurers. Either way, net premium is the smaller number, and the gap between the two is where an insurer's costs and risk-sharing live.
This page covers both meanings, a net premium vs gross premium calculation with real mortality data, gross written premium vs net written premium with published numbers from Lloyd's and the US industry, where the "present value of benefits minus present value of premiums" formula actually belongs, and how state and federal tax rules use gross and net premiums. Figures are as of September 2026. It is general information, not tax or actuarial advice.
Net Premium vs Gross Premium: The Short Answer
The terms show up in four settings, and most confusion comes from mixing them:

If you are a policyholder looking at a quote or a bill, the premium you pay is the gross premium, sometimes with taxes and fees shown on top. "Insurance premium vs gross premium" is usually no difference at all: the insurance premium on your declarations page is the gross premium. The net figures are internal: they describe how the insurer's pricing, reinsurance and taxes work.
What Is Net Premium in Insurance?
In life insurance and annuity pricing, the net premium is the premium that would exactly pay for the promised benefits if the insurer had no costs and made no profit. Actuaries find it with the equivalence principle: at the day the policy is issued, the present value of the net premiums must equal the present value of the expected benefits.
For a policy paid by level annual premiums, that gives the classic net premium formula:
Net level annual premium = present value of future benefits ÷ present value of 1 a year payable while premiums are due
This is not a textbook abstraction. The NAIC's Standard Valuation Law (Model 820), which states have used as the basis for life insurance reserve rules, defines a net level annual premium within its reserve method in close to those words: the present value, at issue, of the benefits provided after the first policy year, "divided by the present value, at the date of issue, of an annuity of one per annum payable on the first and each subsequent anniversary of the policy on which a premium falls due."
Two inputs drive every net premium: a mortality (or morbidity) table, which gives the probability of paying a claim each year, and an interest rate, which discounts future payments. Nothing about the insurer's commissions or overhead enters the calculation. That is what "net" means here.
A single-premium version exists too. The net single premium is simply the present value of the benefits, the lump sum that would fund the policy on day one.
What Is Gross Premium in Insurance?
The gross premium is the net premium plus a loading for everything else the insurer has to pay or earn:
- Acquisition costs: agent or broker commission, often a percentage of premium and highest in the first year.
- Administration: underwriting, issuing the policy, billing, claims handling; partly a flat cost per policy.
- Premium taxes: states tax insurers as a percentage of the premiums they write in the state.
- Profit and risk margin: a cushion for claims running worse than expected, and a return on the capital the insurer ties up.
Because commission, tax and profit are percentages of the gross premium itself, the gross premium is found by dividing, not adding:
Gross premium = (net premium + fixed costs per policy) ÷ (1 − commission rate − premium tax rate − profit margin)
So gross premium is normally the higher figure. The difference, the expense loading, is the part of your premium that never goes toward claims.
Net Premium vs Gross Premium Calculation: A Worked Example
Take a one-year term life policy with a $250,000 death benefit on a 45-year-old man, and use real mortality data. In the CDC's United States Life Tables, 2023, the probability that a man aged 45 dies before 46 is 0.003862. Assume claims are paid at year-end and money earns 4%.
Net premium: $250,000 × 0.003862 ÷ 1.04 = $928.37
Now load it. Assume $75 of fixed cost per policy, a 15% commission, California's 2.35% premium tax rate and a 5% profit margin, all charged on the gross premium:
Gross premium: ($928.37 + $75) ÷ (1 − 0.15 − 0.0235 − 0.05) = $1,003.37 ÷ 0.7765 = $1,292.16
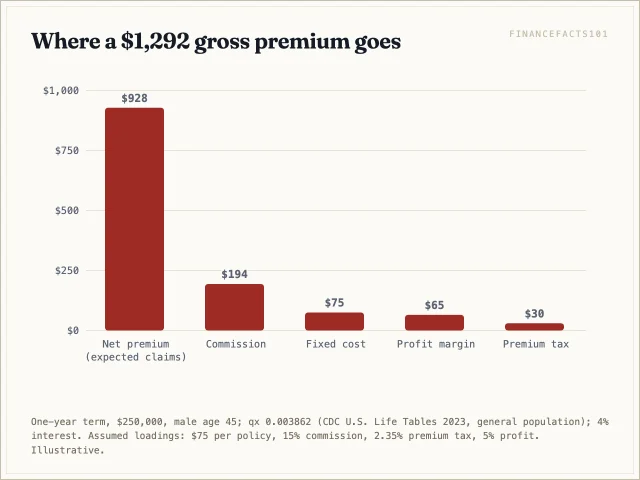
The loading is $363.80, or 28% of the gross premium: $193.82 of commission, $75 of fixed cost, $64.61 of profit margin and $30.37 of premium tax. Two caveats keep this honest. The CDC table covers the whole US population; insurers price with tables of insured lives, who have been screened by underwriting and die at lower rates, so a real quote for a healthy 45-year-old would usually come in lower. And real expense and commission assumptions vary widely by company and product. The structure, though, is exactly this: claims cost plus loadings, divided through.
Gross Written Premium vs Net Written Premium
Property-casualty insurers and reinsurers use "net" in a different sense. Here the question is not what is the premium for but how much of it does the insurer keep.
- Direct premium written: premium on policies the insurer itself issued in the period.
- Assumed premium: premium it took on as a reinsurer of other insurers.
- Gross written premium (GWP): direct plus assumed, before any reinsurance the insurer buys.
- Ceded premium: premium paid away to its own reinsurers.
- Net written premium (NWP): gross written premium minus ceded premium. It measures the risk the insurer keeps on its own balance sheet.
- Earned premium: the part of written premium that corresponds to coverage already provided. A 12-month policy written on October 1 is only one-quarter earned by December 31.
A real example: the Lloyd's market's 2025 annual report shows premiums written of £57,870 million gross, £14,041 million ceded to reinsurers and £43,829 million net. Lloyd's kept about 76% of what it wrote; that share is called the retention ratio.

The US property-casualty industry reports on the same basis. The NAIC's 2025 full-year industry report shows direct premiums written up 4.6% to $1.1 trillion, assumed premiums of $897.8 billion, ceded premiums of $1.0 trillion, and net premiums written up 4.6% to $976.8 billion. The assumed and ceded figures look huge because most of them are premium moved between companies in the same group (88.9% of assumed premium was affiliated), much of which nets out within insurance groups.
Why analysts care about the difference: gross written premium shows how much business an insurer can win; net written premium shows how much risk it is actually carrying and is the base for ratios such as the net writings leverage ratio the NAIC reports (77.3% for the industry in 2025). A fast-growing gross figure with a flat net figure means the insurer is passing the growth on to reinsurers. For the accounting details, see our pages on net premiums written and gross and net written premium income.
Net Premium Reserves: Where "Benefits Minus Premiums" Comes From
A formula that circulates widely, "net premium = present value of policy benefits minus present value of future premiums," is really the formula for a net premium reserve, not for the net premium itself. After a policy has been in force for a while, the benefits still to be paid are worth more than the net premiums still to be collected, because the insured is older and more likely to die. The insurer must hold the difference as a liability.
The Standard Valuation Law puts it in those terms for the commissioners reserve valuation method: the reserve is "the excess, if any, of the present value, at the date of valuation, of the future guaranteed benefits provided for by those policies, over the then present value of any future modified net premiums therefor."
Gross and net premium collide in the same law. Section 8 of Model 820 deals with the case where the gross premium an insurer actually charges is less than the valuation net premium required under the minimum standards; the insurer must then hold a larger reserve, often called a deficiency reserve. In plain terms, if you price a policy below the regulator's own cost of benefits, you have to reserve for the shortfall.
Formula-driven reserves are no longer the whole story. The NAIC notes that "prior to PBR, static formulas and assumptions were used to determine these reserves," and that under principle-based reserving the Valuation Manual became operative on January 1, 2017. Newer life policies are reserved using company experience as well as prescribed formulas.
How Net and Gross Premiums Drive Insurance Company Taxes
Insurers pay taxes on premiums at two levels, and each level uses its own definition of which premiums count and what may be subtracted.

State premium taxes. States tax insurers on the premiums they write in the state. The base is generally gross premiums less a short list of allowed subtractions. California is a clear example. Its Revenue and Taxation Code section 12221 taxes "the amount of gross premiums, less return premiums," and says gross premiums "do not include premiums received for reinsurance and for ocean marine insurance." Section 12202 sets the rate at 2.35%, with separate rates for certain pension and profit-sharing plan contracts. Other states set different rates and allow different subtractions, such as policyholder dividends, so check the statute of the state involved.
Federal income tax, property-casualty insurers. The Treasury regulation at 26 CFR 1.832-4 starts taxable premiums earned from "gross premiums written on insurance contracts during the taxable year, reduced by return premiums and premiums paid for reinsurance." That is net written premium in all but name. For most property-casualty business it then adds 80% of unearned premiums at the start of the year and subtracts 80% of unearned premiums at the end, not 100%, which raises taxable income relative to the books when unearned premiums are growing. The statute sets exceptions, including 100% for certain life-type contracts and different treatment for bond and title business.
Example: gross premiums written $10.0 million, return premiums $0.3 million, reinsurance premiums $2.0 million, so net written premium is $7.7 million. Unearned premiums rise from $4.0 million to $4.5 million over the year. On the books, earned premium is $7.7M + $4.0M − $4.5M = $7.2 million. For tax, it is $7.7M + (80% × $4.0M) − (80% × $4.5M) = $7.3 million, $100,000 more.
Federal income tax, life insurers: the "allowable expenses" rule. Life and annuity insurers cannot deduct all their policy acquisition costs up front. Under Section 848 of the tax code, a portion of their general deductions is capitalized, measured as a percentage of net premiums, which the regulation at 26 CFR 1.848-2 defines as the gross amount of premiums and other consideration, reduced by return premiums and net reinsurance payments. For tax years beginning after 2017 the percentages are 2.09% of net premiums on annuity contracts, 2.45% on group life contracts and 9.2% on other specified contracts such as individual life, and the capitalized amount is deducted over 180 months starting in the second half of the year.
Example: a life insurer with $200 million of net premiums on individual life policies capitalizes up to 9.2%, or $18.4 million, of its general deductions (the amount is capped at those actual deductions). It deducts $18.4M × 6/180 = about $613,000 in the first year and about $1.23 million in each full year after. The statute allows a 60-month period for the first $5 million of capitalized expenses, but that allowance shrinks dollar for dollar once capitalized expenses pass $10 million, so this insurer gets none of it.
Other Everyday Meanings of Net and Gross Premium
Outside actuarial and tax work, two more uses are common:
- Agency and broker statements. An agent collects the gross premium from the client, keeps its commission and sends the insurer the rest, which agency paperwork often calls the net premium. On a $1,000 policy with 15% commission, the insurer's net premium is $850.
- Your own bill. Surcharges, policy fees and, for some policies, state taxes can appear as separate lines on top of the premium. The premium line is the gross premium for the coverage; the fees are extra.
If you are shopping for life insurance, none of the net figures appear on your quote. What you can control is the gross premium, by comparing quotes, choosing term length and amount carefully, and understanding how much life insurance you need in the first place. If a whole-life policy lapses, state nonforfeiture law, built on the same present-value arithmetic, sets the minimum cash value you are owed; see our page on the nonforfeiture clause for what you are entitled to.
FAQ
Is net premium higher or lower than gross premium?
Lower, in every meaning. The actuarial net premium excludes expenses, commissions, taxes and profit; net written premium excludes premium ceded to reinsurers; an agent's net premium excludes commission. Only in unusual cases, such as a policy priced below the regulator's minimum standard, does the relationship invert, and the insurer must then hold a deficiency reserve.
What is the formula for net premium?
For a level-premium life policy: net premium = present value of expected benefits ÷ present value of 1 a year payable while premiums are due. For a single-premium policy, net premium = present value of expected benefits. In property-casualty accounting, net written premium = gross written premium − ceded reinsurance premium.
What is the difference between gross written premium and net written premium?
Gross written premium is all the premium an insurer writes, directly and as a reinsurer, before buying its own reinsurance. Net written premium is what remains after subtracting premium paid to its reinsurers. In 2025 Lloyd's wrote £57.9 billion gross and £43.8 billion net.
Is premium tax charged on gross or net premium?
Usually on gross premiums written in the state, less return premiums and a few other items the state allows. California, for example, taxes gross premiums less return premiums at 2.35% and excludes reinsurance and ocean marine premiums from the base. Rules differ by state.
Sources
- NAIC, Standard Valuation Law, Model 820 — Section 5 (net level annual premium, commissioners reserve valuation method) and Section 8 (valuation net premium exceeding the gross premium)
- NAIC, Principle-Based Reserving — Valuation Manual operative January 1, 2017
- NAIC, U.S. Property & Casualty and Title Insurance Industries – 2025 Full Year Results — direct, assumed, ceded and net premiums written
- Centers for Disease Control and Prevention, NCHS, United States Life Tables, 2023 (National Vital Statistics Reports Vol. 74 No. 6, July 15, 2025) — Table 2, male qx at age 45
- Treasury regulation, 26 CFR 1.832-4 — premiums earned for property-casualty insurers
- Treasury regulation, 26 CFR 1.848-2 — determination of net premiums; 26 U.S.C. 848 for the 2.09% / 2.45% / 9.2% percentages, the 180-month period and the $5 million / 60-month rule
- California Revenue and Taxation Code, section 12221 and section 12202 — premium tax base and 2.35% rate
- Lloyd's, 2025 Annual Report — note 20 (premiums written gross, reinsurance, net) and note 24 (five-year summary)
 Next entry · No. 3,426Understanding Net Premiums Written: A Crucial Metric for Insurance Companies
See also
-
No. 3,426
27 Mar 2025
20 min
Understanding Net Premiums Written: A Crucial Metric for Insurance Companies
Insurance
-
 No. 5,201
19 Aug 2025
20 min
Underwithstanding Taxes: Underwithholding vs Overwithholding
Taxation
-
 No. 4,898
26 Jul 2025
17 min
Maximizing Your Tax Shield: A Comprehensive Guide for Investors
Business Finance
-
 No. 4,698
10 Jul 2025
23 min
Understanding Sole Proprietorships: Advantages, Disadvantages, and Taxation
Business Strategy
-
 No. 4,585
30 Jun 2025
21 min
Understanding IRS Section 1245: Recapturing Depreciation on Gains from Section 1231 Property
Taxation
-
 No. 4,358
12 Jun 2025
22 min
A Comprehensive Guide to Understanding Reimbursement: From Business Expenses and Insurance to Taxes and Legal Matters
Business Finance