The Unauthorized Trades of Jérôme Kerviel: A Rogue Trader Case Study
Jérôme Kerviel hid a €49 billion futures bet at Société Générale; unwinding it in January 2008 cost €4.9 billion. How he did it, how it ended, the verdicts.
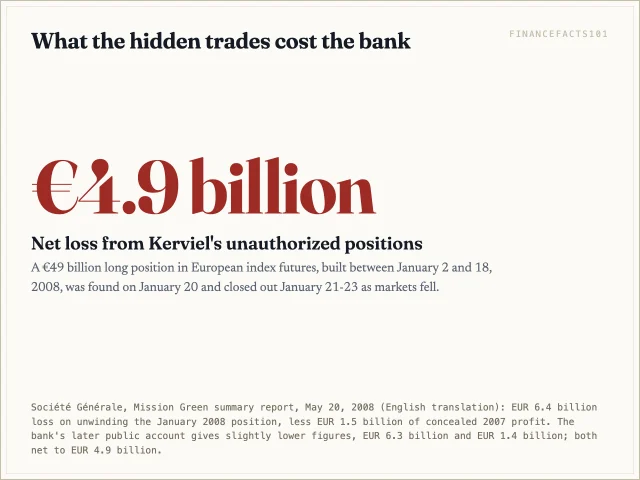
Jérôme Kerviel is the former Société Générale trader whose hidden bets on European stock index futures cost the French bank €4.9 billion in January 2008. His job was low-risk arbitrage. Instead, he built huge one-way positions, peaking at a €49 billion bet that markets would rise, and disguised them with fictitious offsetting trades. The bank found the positions over the weekend of January 19-20, 2008, closed them out over the next three trading days as markets fell, and announced the loss on January 24.
A Paris court convicted Kerviel in 2010 of forgery, breach of trust and unauthorized computer use, and sentenced him to five years in prison, two of them suspended. Later courts upheld the conviction. The €4.9 billion he was first ordered to repay was cut to €1 million in 2016, after an appeals court found the bank's own control failures had contributed to the loss. The case is still one of the largest trading losses by a single employee on record, and a standard case study in operational risk.
This page covers who Kerviel is, what he traded, how the concealment worked, how the bank found it, the court cases, the argument over whether his managers knew, and how the case compares with other rogue trader losses. Sources are court rulings as reported by the Associated Press and other outlets, the bank's own investigation, and US regulators' definitions. Where the bank's account and Kerviel's differ, this page says so.
Who Is Jérôme Kerviel?
Kerviel is from western Brittany, the Associated Press noted in 2010. He joined Société Générale in 2000 and worked in back-office roles, among the teams that record, check and settle trades, before moving to the trading floor in 2005, according to Al Jazeera's January 2008 report. Société Générale says in its own account of the Kerviel case that he spent more than two years as an assistant trader and knew the people in the control functions personally. That background mattered. The bank says he used his "detailed knowledge of the control systems" to get around them.
On the trading floor he worked on the Delta One desk, which trades products designed to track an underlying index or stock one for one. His assignment, according to the bank's internal investigation, was arbitrage on turbo warrants, leveraged products the bank sold to investors. The bank would buy a competitor's mispriced warrant and hedge it with index futures, aiming to capture a small, low-risk price difference.
He was not highly paid by trading-floor standards. The bank says his fixed salary was €48,500 in 2007. He received a €60,000 bonus for 2006 and asked for €600,000 for 2007, based on the €55 million of profit he had officially reported for that year. Bank executives told the Associated Press in January 2008 that his salary and bonus came to less than €100,000.
The Derivatives He Traded: Index Futures in Plain English
A futures contract is, in the SEC's investor.gov definition, "an agreement to buy or sell a specific quantity of a commodity or financial instrument at a specified price on a particular date in the future." An index future does this for a stock market index. Kerviel's positions were in futures on three European indices, the Euro Stoxx, Germany's DAX and London's FTSE, Al Jazeera reported. If you buy an index future, you are long: you gain if the index rises and lose if it falls. If you sell one, you are short and the reverse applies.
Two features of futures made the case possible.
Leverage. A futures position controls a large notional amount, the full value of the index exposure, while the trader posts only a fraction of that as margin. A bank can therefore hold tens of billions of euros of exposure without paying tens of billions up front. Kerviel's €49 billion position, the bank said, was about one and a half times its entire capital.
Offsetting positions. A hedged book pairs a long position with a short one, so the net market risk is small even when the gross amounts are large. Kerviel's job was supposed to look like that. His fraud made unhedged positions look hedged by booking fake offsetting trades.
Index futures trade on electronic exchanges, similar in principle to the CME Globex platform in the United States. For how futures fit alongside other financial instruments, see our entry on debt, equity and derivatives.
How Kerviel's Unauthorized Trades Worked
Société Générale's General Inspection department investigated the fraud and published a summary, the Mission Green report of May 20, 2008, in English translation. Its central finding is the evidence behind the "directional trading" description: "The fraud consisted of the taking of massive directional positions which JK hid, together with their risks and their earnings." A directional position is a straight bet on which way the market goes, with nothing on the other side to offset it. It is the opposite of the hedged arbitrage his job called for.
The report found three concealment techniques:
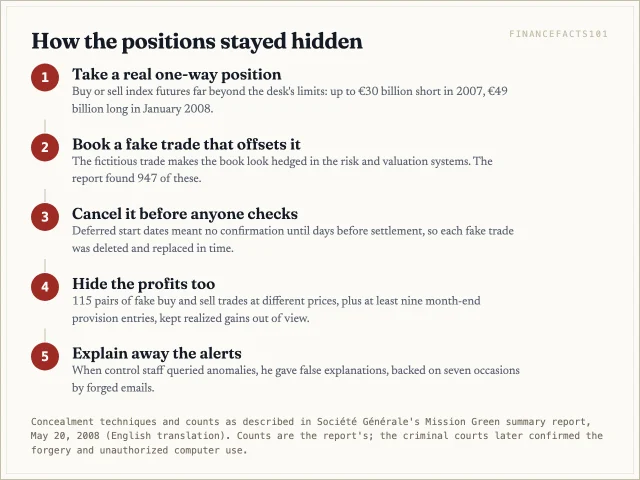
- Fictitious trades that were entered and then cancelled. Kerviel booked fake trades designed to offset his real positions in the risk and valuation systems. The investigators identified 947 of them. He often gave them a deferred start date. Such trades are not confirmed until a few days before they start, which gave him time to cancel each one and replace it with a new fake trade before anyone checked it with a counterparty.
- Pairs of fake buy and sell trades at different prices. These made realized profits disappear from view. On March 1, 2007, for example, he booked a purchase and a sale of the same 2,266,500 SolarWorld shares at €63 and €53. That created a fictitious loss of €22.7 million without creating any position. The report counted 115 such trades.
- Provisions booked within the month. He used adjustments that are normally reserved for trading assistants to hide profits during a month, since provisions were checked only at month end. The report found at least nine.
When control staff asked questions, the report says, he gave untruthful answers and on seven occasions supported them with forged emails.
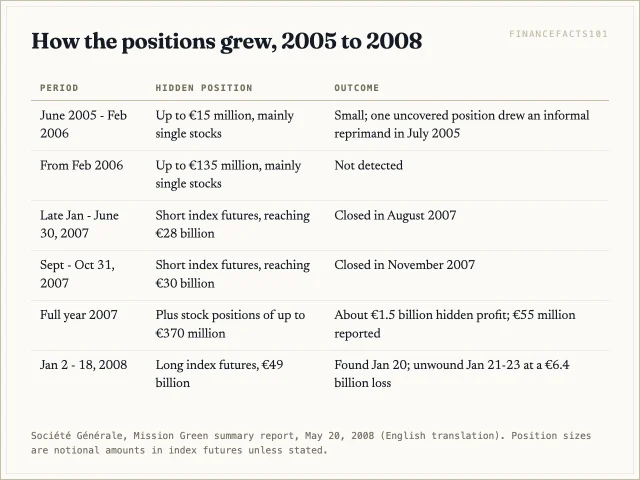
The positions grew in stages. In 2005 and 2006 the fraudulent trades were relatively small, up to €135 million. In 2007 he built a short position in index futures that reached €28 billion on June 30, closed it in August, then built another that reached €30 billion by October 31. Those bets made money, and he finished 2007 with about €1.5 billion of hidden profit, against the €55 million he reported. Between January 2 and January 18, 2008, he reversed direction and built a €49 billion long position. The market then fell.
Discovery and the €4.9 Billion Loss
On January 18, 2008, an alert led the bank to one fictitious trade, and a team searched the books over the weekend. By January 20 it had found the full position. The bank says the positions were more than its capital, so it could not keep them. After consulting the Governor of the Banque de France and the Secretary General of the AMF, France's markets regulator, it decided to close them out quickly and in secret. It did so between January 21 and 23, 2008. The bank says it kept its trading within 10% of market volumes.
The timing could hardly have been worse. World stock markets "fell hugely" on January 21 and 22, as a Fitch Ratings director told the AP. In the United States, the Federal Reserve made an unscheduled cut of 75 basis points on January 22, 2008, "in view of a weakening of the economic outlook and increasing downside risks to growth." Société Générale had not yet disclosed anything.
On January 24, the bank announced the fraud, a €4.9 billion loss, and a plan to raise €5.5 billion of new capital, the Associated Press reported. CEO Daniel Bouton offered to resign, and the board refused.
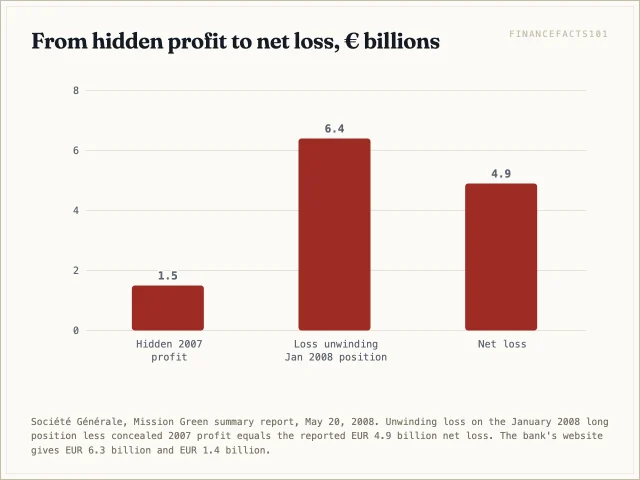
The €4.9 billion is a net figure. The Mission Green report puts the loss from unwinding the January 2008 position at €6.4 billion, offset by the €1.5 billion of hidden 2007 profit. The bank's later public account gives slightly lower figures, €6.3 billion and €1.4 billion. Both versions give the same €4.9 billion net loss, which the bank says was audited and was confirmed by France's highest court in 2014.
The Operational Incident: Why the Controls Failed
Banks classify a loss like this as operational risk, not market risk. The bank did not lose money because it chose to take a market bet. It lost money because its processes failed to stop an employee taking one. US bank capital rules define operational risk as "the risk of loss resulting from inadequate or failed internal processes, people, and systems or from external events," and list internal fraud as the first of seven event types, covering acts by "at least one internal party" intended "to defraud, misappropriate property, or circumvent regulations, the law, or company policy" (12 CFR 217.101). Kerviel's trades are a textbook internal-fraud loss event.
The Mission Green report found that the controls in the support functions were carried out as designed. The problem was that the controls needed to catch this kind of fraud did not exist. Its findings on the trading side were blunter:
- Unsupervised months. From January 12 to April 1, 2007, when he started building his large positions, Kerviel's desk had no direct manager after the previous one resigned, and no interim arrangement.
- Tolerated directional trading. His earlier manager had tolerated intraday directional bets unrelated to his assignment. In July 2005 that manager caught an uncovered overnight position of about €10 million in Allianz shares and gave only an informal reprimand.
- Ignored alerts. The investigators catalogued 74 alerts about his trades. Thirty-nine had a direct link to the fraud and could have exposed it if followed up.
- Unused signals. His reluctance to take vacation was raised four times without effect. Profits growing far beyond what the strategy should produce did not trigger scrutiny.
France's banking regulator, the Commission bancaire, reached similar conclusions. In July 2008 it issued a formal reprimand and fined Société Générale €4 million for serious deficiencies in its internal controls, Reuters reported (about $6.3 million, per the Associated Press). It cited "significant weaknesses" in computer security and said traders and the staff meant to monitor them were not independent enough of each other.
The Court Cases: Conviction, Appeals and Damages
The criminal and civil cases ran for more than a decade. The key rulings:
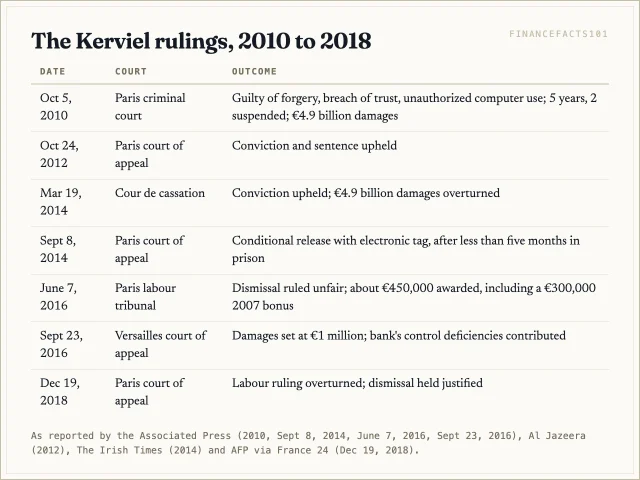
First trial, 2010. On October 5, 2010, the Paris criminal court convicted Kerviel on all counts: forgery, breach of trust and unauthorized computer use. It sentenced him to five years, with two suspended, and ordered him to repay the full €4.9 billion, the Associated Press reported. The presiding judge said the evidence "does not allow us to deduce that Societe Generale was aware of Jerome Kerviel's fraudulent activities," Al Jazeera reported.
Appeal, 2012. On October 24, 2012, the Paris appeals court upheld the conviction, calling Kerviel "the sole creator, inventor and user of a fraudulent system," Al Jazeera reported.
Supreme court, 2014. On March 19, 2014, France's highest court, the Cour de cassation, upheld the criminal conviction but overturned the €4.9 billion damages award. It said the lower court had not taken account of the bank's own faults, The Irish Times reported. Kerviel went to prison later that year. He left prison on conditional release on September 8, 2014, and was fitted with an electronic tag, the Associated Press reported. He had served less than five months and was placed under a nightly curfew, Fortune reported.
Damages retrial, 2016. On September 23, 2016, the Versailles appeals court set the damages at €1 million. It found Kerviel "partly responsible" but said the bank's "deficiencies" in management, controls and security had contributed to the size of the loss, the Associated Press reported.
Employment case, 2016 to 2018. In June 2016 a Paris labour tribunal ruled his dismissal unfair and ordered the bank to pay him about €450,000, the Associated Press reported. That included a €300,000 bonus for 2007. On December 19, 2018, the Paris Court of Appeal overturned that ruling and held that the bank was justified in firing him, AFP reported.
Conflicting Accounts: Did Société Générale Know?
Kerviel has never denied taking the positions or hiding them. His defence has always been that his managers knew, or chose not to know, and tolerated his risk-taking while it made money. In January 2008 his lawyers said he "did not profit in any way". The bank's investigation found no sign that he took money for himself.
The bank's position is that he deceived it. Mission Green concluded that "neither JK's hierarchical superiors nor his colleagues were aware of the fraudulent mechanisms used or of the size of his positions." The criminal courts agreed that he alone was criminally responsible.
The two positions are closer than they sound. The same report that cleared his managers of knowing about the fraud also criticised them heavily for weak supervision, tolerance of directional trading and inattention to alerts. It found indications that a middle-office assistant may have helped enter some fictitious trades, but said this had to be confirmed by the courts. The 2016 Versailles ruling put part of the financial responsibility on the bank. That is also why the civil damages fell from €4.9 billion to €1 million. The courts found a fraud by one man, made possible by an organisation that was not watching closely.
The case also had a tax dimension. Société Générale deducted the loss for tax purposes and received a tax credit of about €2.2 billion in 2009 and 2010. After the 2016 Versailles ruling put part of the responsibility on the bank, the French tax authority notified it in spring 2017 of a €2.2 billion reassessment, franceinfo reported in January 2018, citing Le Canard Enchaîné. The bank declined to comment, citing tax confidentiality. It said in the same statement that the Versailles ruling did not undermine the tax treatment of the loss, and that a legal dispute over it remained possible.
Jérôme Kerviel's Net Worth and Life After the Case
There is no reliable public figure for Kerviel's net worth, and sites that print one are guessing. What the record shows is modest earnings and a large debt. His pay at the bank was a €48,500 salary plus bonus. In 2010 the AP reported he was earning about €2,300 a month as a computer consultant, and French media calculated that repaying €4.9 billion at that rate would take 177,536 years. The civil debt was cut to €1 million in 2016, a ruling the bank's lawyer called enforceable, while Kerviel said he hoped to get it to zero. On his release in 2014, his lawyer said he planned to join a software consulting firm.
He has stayed a public figure in France. He published a memoir, L'engrenage: mémoires d'un trader, in 2010, and a film based on it, L'Outsider, came out on June 22, 2016, according to Société Générale's account. In 2014, before going to prison, he made a walking pilgrimage from Rome back toward France after meeting Pope Francis, The Irish Times reported.
Kerviel Compared With Other Rogue Trader Cases
Kerviel's loss is often compared with other unauthorized trading cases. They share a pattern: a trader who understands the back office, growing profits nobody questions, hidden positions, and controls that record trades but do not challenge them. Our entry on rogue traders covers the wider history.
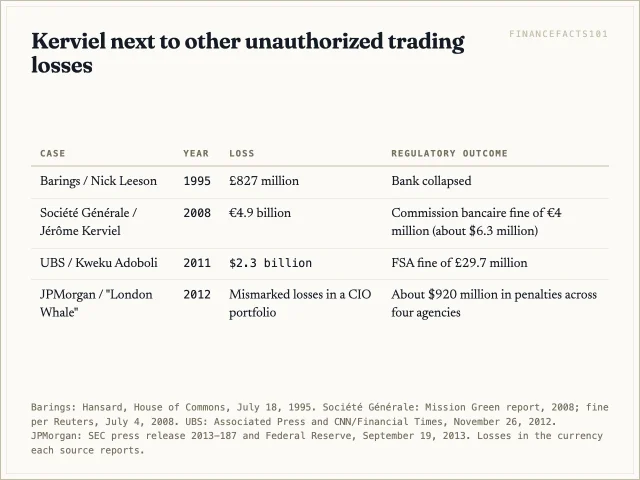
- Barings, 1995. Nick Leeson's unauthorized and concealed trading at Barings Futures Singapore left cumulative losses of £827 million, measured after the bank collapsed on February 26, 1995, the UK Chancellor told Parliament in July 1995.
- UBS, 2011. Kweku Adoboli lost $2.3 billion on UBS's London exchange-traded funds desk in 2011, CNN reported. In November 2012 the UK's Financial Services Authority, which was the regulator at the time, fined UBS £29.7 million for control failures, the Associated Press reported. Adoboli was sentenced to seven years.
- JPMorgan "London Whale," 2012. This was not a single rogue trader, but it is a close cousin. In September 2013 the SEC charged JPMorgan with lacking internal controls to stop traders "fraudulently overvaluing investments to conceal hundreds of millions of dollars in trading losses." JPMorgan paid a $200 million SEC penalty and admitted wrongdoing. The Federal Reserve imposed its own $200 million penalty for oversight and control deficiencies, and total penalties across agencies came to about $920 million.
Lessons for Risk Management
The fixes Société Générale says it made after 2008 read like a list of what failed. It points to monitoring of nominal (gross) amounts as well as net risk, monitoring of trade cancellations, checks on staff who do not take vacation, a new cross-functional security department, and bonuses that are capped, deferred and subject to clawback. It says it has spent more than €200 million on the security of its market activities since 2008. For anyone who runs, audits or invests in a trading business, the case leaves five lessons:
- Watch gross positions, not just net risk. A book that nets to zero can hide two enormous one-way bets. The Commission bancaire specifically highlighted the lack of a gross trading limit for Kerviel, Al Jazeera reported.
- Treat cancelled and amended trades as a warning sign. Hundreds of trades booked and deleted before settlement were the core of the concealment.
- Investigate unexplained profit as hard as unexplained loss. A turbo-warrant arbitrage desk does not make €1.5 billion in a year.
- Keep the middle office independent and staffed. The investigators found that the control teams were stretched while volumes doubled.
- Enforce time away from the desk. Kerviel's concealment needed constant upkeep, with fake trades cancelled and replaced before they could be checked. A trader who never takes leave never lets anyone else see the book.
FAQ
What did Jérôme Kerviel do?
He took huge, unauthorized bets on European stock index futures while working at Société Générale, and hid them by booking fictitious offsetting trades. He built short positions of up to €30 billion in 2007 and a €49 billion long position in January 2008. He was convicted in 2010 of forgery, breach of trust and unauthorized computer use.
How much money did Kerviel lose Société Générale?
€4.9 billion, net. Closing out his January 2008 position lost about €6.4 billion, according to the bank's investigation, and that was partly offset by roughly €1.5 billion of hidden profit from his 2007 trades. France's highest court confirmed the amount in 2014.
Did Jérôme Kerviel go to prison?
Yes. He was sentenced in 2010 to five years with two suspended. After his appeals failed he went to prison in 2014 and was released that September under an electronic tag and curfew, having served less than five months.
What is Jérôme Kerviel's net worth?
No reliable figure has been published. His bank pay was modest, a €48,500 salary in 2007, and he was left owing Société Générale €1 million in civil damages after a 2016 ruling reduced the original €4.9 billion award. Any specific net worth number online is an estimate, not a documented figure.
Did Société Générale know about Kerviel's trades?
The courts found that he acted alone and that the bank did not know. The bank's own investigation found no evidence that his managers knew about the fraud, but criticised their supervision and a long list of ignored alerts. A 2016 appeals court held the bank partly responsible for the size of the loss. Kerviel maintains that his superiors tolerated his trading.
Sources
- Société Générale General Inspection Department, Mission Green summary report (May 20, 2008), English translation: concealment techniques (947 fictitious trades, 115 reverse-trade pairs, provisions), positions by period, €6.4 billion unwinding loss and €1.5 billion 2007 profit, 74 alerts, supervision findings
- Société Générale, Kerviel case newsroom page (updates of June 2016): the bank's account of discovery and unwinding, 2007 pay and bonus figures, €125 million desk limit, labour tribunal award of about €450,000, control measures and spending since 2008
- U.S. Securities and Exchange Commission, Investor.gov, Futures contract (glossary)
- Electronic Code of Federal Regulations, 12 CFR 217.101, definitions of operational risk and operational loss event types
- Board of Governors of the Federal Reserve System, FOMC statement of January 22, 2008 and JPMorgan Chase & Co. to pay $200 million (September 19, 2013)
- U.S. Securities and Exchange Commission, JPMorgan Chase Agrees to Pay $200 Million and Admits Wrongdoing to Settle SEC Charges (September 19, 2013)
- Associated Press via Deseret News, Societe Generale uncovers massive fraud by futures trader (January 24, 2008) and French rogue trader damages slashed to 1 million euros (September 23, 2016)
- Associated Press via NBC News, Bank fined for $7.8 billion rogue trader scandal (July 5, 2008) and Ex-trader jailed, told to repay $6.7 billion (October 5, 2010)
- Al Jazeera, French trader's custody extended (January 27, 2008), French 'rogue trader' found guilty (October 5, 2010) and French rogue trader Kerviel loses appeal (October 24, 2012)
- The Irish Times, Court upholds 'rogue trader' Kerviel's prison sentence (March 19, 2014)
- Fortune, French rogue trader Kerviel to go free next week (September 5, 2014)
- France 24 (AFP), French court annuls dismissal payout to 'rogue trader' Kerviel (December 19, 2018)
- Associated Press via Fox News, French bank ordered to pay $510,000 to ex-trader Kerviel (June 7, 2016) and French ex-trader Kerviel leaves prison (September 8, 2014)
- Reuters via BFM Bourse, Un blâme et une amende de 4 millions d'euros pour la SocGen (July 4, 2008)
- franceinfo, Affaire Kerviel : le fisc réclame 2,2 milliards d'euros à la Société générale (January 17, 2018)
- Al Jazeera, SocGen fined for rogue trading loss (July 4, 2008)
- CNN Business (Financial Times), FSA fines UBS £29.7m over rogue trader (November 26, 2012)
- UK Parliament, Hansard, Barings, House of Commons debate (July 18, 1995)
- Associated Press via The Christian Science Monitor, UBS fined. Rogue trader lost $2.3 billion. (November 26, 2012)
 Next entry · No. 2,590Jerry A. Hausman: Economist, Consultant, and Data Scientist behind Amazon’s Retail Optimization
See also
-
 No. 2,444
07 Jan 2025
19 min
Understanding Interest Rate Futures: A Comprehensive Guide for Institutional Investors
Business Finance
-
 No. 2,443
06 Jan 2025
15 min
Interest Rate Floors: Meaning, Bank Loans, Floor Options, and Floor vs Cap
Business Finance
-
 No. 2,161
15 Dec 2024
19 min
Understanding Holdovers: An Overview of Transactions that Have Not Yet Been Processed
Business Finance
-
 No. 1,498
24 Sep 2024
21 min
A Comprehensive Guide to Finance: History, Public, Corporate, and Personal
Business Finance
-
 No. 3,678
18 Apr 2025
20 min
Understanding the Role of Bank Holding Companies: Regulation, Structure and Function
Business Finance
-
 No. 3,545
07 Apr 2025
19 min
Understanding Nonperforming Assets: Definition, Effects, and Recovery Strategies for Investors
Business Finance