Interest Rate Floors: Meaning, Bank Loans, Floor Options, and Floor vs Cap
An interest rate floor is the lowest rate a loan or contract will use, however far the index falls. How floors work, with a 0.50% SOFR floor example.
An interest rate floor is the lowest interest rate a loan or financial contract will use, no matter how far its benchmark falls. In a floating-rate loan, the floor keeps the rate the borrower pays from dropping below a set level. As a stand-alone derivative, a floor is an option that pays its buyer whenever the benchmark rate falls below an agreed strike.
A cap does the opposite. It sets the highest rate, protecting whoever pays the interest. A floor protects whoever receives it: the lender, the bank, or the investor. Everything below explains how floors show up in bank loans, how the option version pays out, and how floors compare with caps, ceilings, collars, and swaps, with the dollar math on each. Rates quoted are as of September 2026. This is general information, not advice about any particular loan or hedge.
Interest Rate Floor Meaning: What "Floor Rate" Means
A floor only makes sense next to a rate that moves. A fixed-rate loan never needs one, because its rate cannot fall. A floating-rate loan resets on a schedule to a benchmark (also called an index, today usually SOFR, the Secured Overnight Financing Rate, or the prime rate) plus a fixed margin or spread. The floor is a minimum written into that formula.
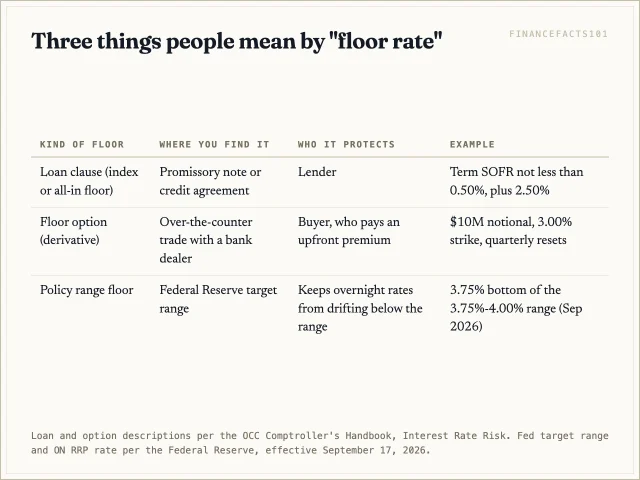
So when someone asks what a floor rate means, there are three common answers, and the context tells you which one applies:
- A loan clause. The contract says the benchmark, or the whole rate, "shall not be less than" some figure. Business loans, lines of credit, and many adjustable-rate mortgages have one.
- A derivative. An interest rate floor bought from a bank dealer pays cash when the benchmark sits below the strike. The buyer pays a premium up front for that protection.
- A policy or market boundary. The Federal Reserve's target range for the federal funds rate literally has a floor and a ceiling. After its September 2026 meeting the Fed set the range at 3.75% to 4.00%, and its implementation note set the overnight reverse repo rate, which works as a soft floor under money-market rates, at 3.75%.
The loan clause and the derivative are two forms of the same thing. The bank's regulator says so directly: the OCC's Comptroller's Handbook on interest rate risk describes a cap or floor inside a loan as an option held by one side, with the cap or floor rate as the strike price. "When market interest rates decline below the floor, the bank's option moves 'in the money' because the rate paid on the loan is higher than the market rate." A borrower who signs a loan with a floor has, in effect, sold the lender a floor option, usually without an explicit price. Any payment for it has to come through the rest of the loan's terms, which is why it is worth negotiating over (see How to Read and Negotiate a Floor, below).
Interest Rate Floors in Bank Loans
Most business borrowing is floating-rate, which is why floors matter far more in commercial lending than on consumer products. Federal Reserve staff estimated in a 2017 FEDS Note that, as of March 2017, roughly 85% of outstanding corporate loans (term loans and credit lines), about $2.2 trillion of $2.6 trillion, carried floating rates. The floating-rate share comes from large bank holding companies' FR Y-14 supervisory data, which the authors assumed was representative of all corporate loans on bank holding companies' balance sheets; loans held outside banks were estimated from the Fed's Financial Accounts. They also found that "the majority of term loans with floating rates, and a nontrivial fraction of lines of credit, have floors."
Floors in loans come in two shapes, and the difference is easy to miss when reading a term sheet:
- Index floor (benchmark floor). The benchmark is floored, then the margin is added on top. "Term SOFR, but not less than 0.50%, plus 2.50%" can never charge less than 3.00%.
- All-in floor (rate floor). The final rate is floored. "Term SOFR plus 2.50%, but not less than 4.00%" can never charge less than 4.00%. An all-in floor set well above the margin bites much sooner.
Levels vary by contract, borrower, and year. A real example from the SEC's EDGAR database shows the spread inside a single deal: the acquisition financing commitment Wells Fargo gave MaxLinear in May 2022 defined the floor as 0.00% for the revolving credit facility and 0.50% for the Term B loan, applied to Adjusted Term SOFR. The 0.00% floor on the revolver only stops the benchmark from going negative. The 0.50% floor on the term loan charged real money whenever SOFR sat near zero, and in 2021 it sat there all year.
Floors in small-business loans follow the same pattern but are usually written against the prime rate or an all-in minimum, and they are negotiated deal by deal. The number is in the promissory note. If a banker describes a loan as "prime plus 1" without mentioning a minimum, ask whether the note has one before signing.
How an Interest Rate Floor Works at Each Reset
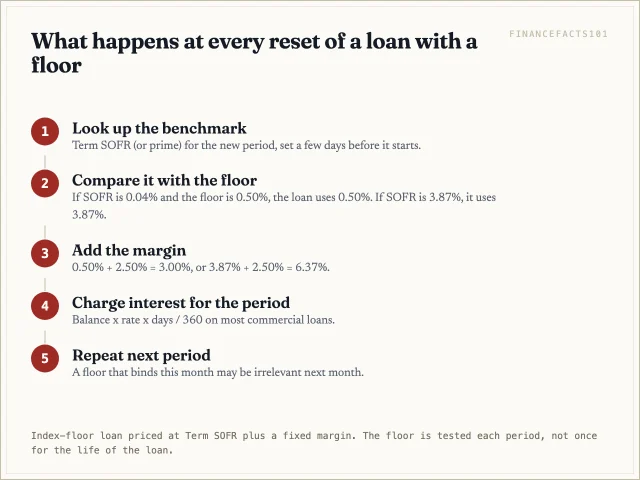
A floor is checked every time the loan resets, not once over its life. On a loan that resets monthly, that means twelve separate tests a year. In each one the lender looks up the benchmark for the period, compares it with the floor, uses whichever is higher, and adds the margin. If rates fall below the floor for three months and then recover, the floor affects exactly those three months and nothing else.
That is also why a floor can sit dormant for years and still matter. When the Fed cut its target range to 0% to 0.25% in March 2020 and held it there until March 2022, loans with any positive floor were paying the floor rate for roughly two years straight.
Worked Example: A $2 Million Loan With a 0.50% SOFR Floor
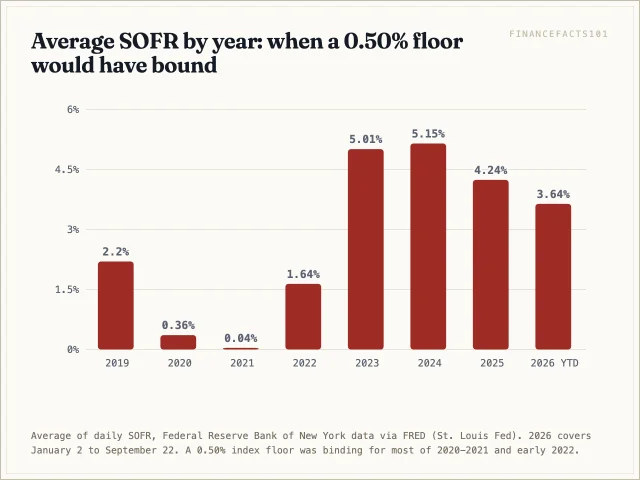
Take a $2,000,000 commercial loan priced at Term SOFR plus 2.50%, with a 0.50% index floor. Use the average of daily SOFR as a stand-in for the Term SOFR each reset would use; the two track closely. Per the St. Louis Fed's SOFR series, overnight SOFR averaged 0.04% across 2021. It printed 3.87% on September 22, 2026.
In 2021, the floor binds. Without it, the rate would have been 0.04% + 2.50% = 2.54%. With it, SOFR is treated as 0.50%, so the rate is 3.00%. The gap of 0.46 percentage points on $2,000,000 is about $9,200 a year of extra interest, a little more on the actual/360 day count most commercial loans use.
In September 2026, the floor is irrelevant. SOFR at 3.87% is far above 0.50%, so the rate is 3.87% + 2.50% = 6.37%, the same as it would be with no floor at all.
Swap in a 4.00% all-in floor and the picture changes. Now the rate cannot fall below 4.00%. In 2021 the borrower would have paid 4.00% instead of 2.54%, an extra 1.46 points, or about $29,200 a year. This floor binds whenever SOFR is below 1.50%, three times the index floor's trigger.
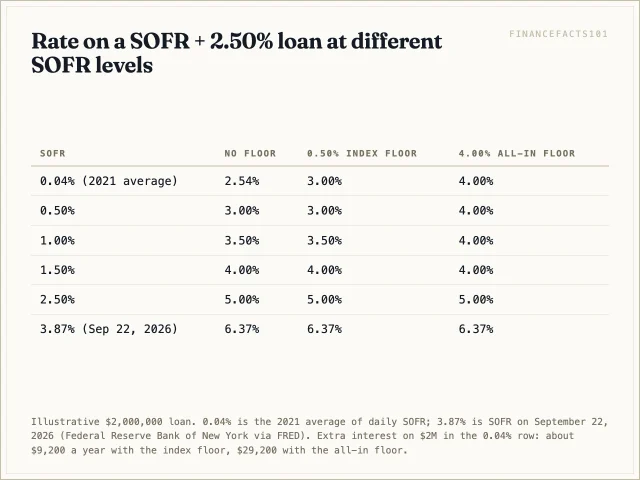
The lesson for a borrower is where the floor sits relative to today's benchmark. With SOFR near 3.9%, a 0.50% index floor costs almost nothing in expected terms, and it is rarely worth spending negotiating capital on. An all-in floor close to the current rate is a different animal: it quietly converts much of a floating-rate loan into a loan whose rate can go up but not down.
Interest Rate Floor Options: The Derivative Version
An interest rate floor option is a contract, usually bought over the counter from a bank dealer under an ISDA master agreement rather than on an exchange, that pays the buyer when a floating benchmark is below the strike rate on each reset date. It is a series of separate put options on the rate, one per period, known as floorlets. The buyer pays a premium, normally up front, and has no further obligation. The seller keeps the premium and pays out if rates fall.
The payout for each period is:
Notional × max(0, strike − benchmark) × days in period ÷ 360
Take a $10,000,000 notional floor with a 3.00% strike, quarterly resets, and 90-day periods:
- Benchmark at 3.87% (September 2026 level): pays $0.
- Benchmark at 2.50%: pays $10,000,000 × 0.50% × 90/360 = $12,500 for that quarter.
- Benchmark at 1.00%: pays $50,000 for that quarter.
- Benchmark at 0.04% (2021 average): pays $74,000 for that quarter.
The notional itself never changes hands. Only the difference in rates is paid, usually in arrears at the end of each period.
The premium depends on the strike relative to the forward rate curve, the term, and how volatile rates are expected to be, so it can only be quoted by a dealer on the day. A floor struck far below today's rates is cheap because it is unlikely to pay. A floor struck near or above expected rates is expensive for the opposite reason.
Who buys floors? Anyone whose income falls when rates fall. That includes banks with large books of floating-rate loans, investors holding floating-rate notes, and pension or insurance portfolios that need a minimum yield. Borrowers rarely buy them. Borrowers more often sell a floor to pay for a cap, which is the collar described below.
Interest Rate Floor vs. Cap (and Ceiling, Collar, and Swap)
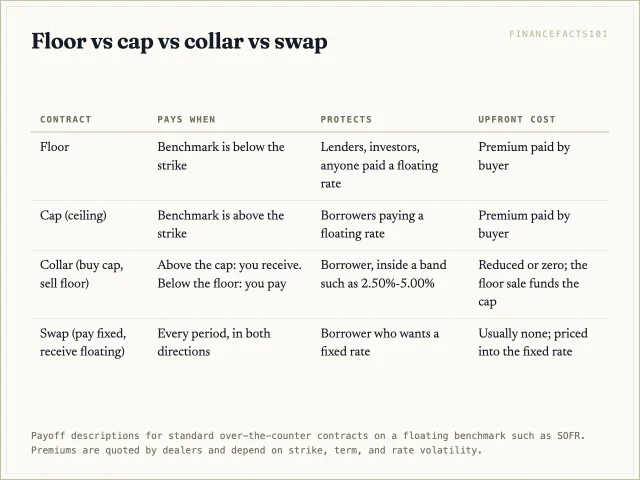
The single most searched comparison is floor versus cap, and the answer fits in one sentence: a cap sets the maximum rate and protects the borrower from rising rates; a floor sets the minimum rate and protects the lender or investor from falling rates.
Floor vs. ceiling. A ceiling is another word for a cap. "Floor rate and ceiling" in a loan means the band the rate is allowed to move in. On an adjustable-rate mortgage, for example, the lifetime cap is the ceiling and the minimum rate is the floor.
Cap and floor together: the collar. A borrower worried about rising rates can buy a cap and pay for it by selling a floor on the same benchmark and notional. If the premiums offset, the result is sometimes called a zero-cost collar. Buy a 5.00% cap and sell a 2.50% floor, and the borrower's effective benchmark is held inside 2.50% to 5.00%. The trade-off is plain: the borrower gives up the benefit of rates falling below 2.50% in exchange for protection above 5.00%.
Floor vs. swap. An interest rate swap exchanges a floating rate for a fixed one in both directions. It locks the rate; there is no upside and usually no upfront premium. A floor is one-way: it pays when rates fall and costs nothing more when they rise, and you pay for that asymmetry up front.
One practical trap sits where loans and swaps meet. If a borrower's loan has a 0.50% SOFR floor and the borrower fixes the rate with a swap that has no floor, then when SOFR drops below 0.50% the loan keeps charging 0.50% while the swap pays the borrower only actual SOFR. The hedge leaks. Hedge desks deal with this by embedding a matching floor in the swap, which costs a little more. Ask for it when the loan has one.
Floors in Adjustable-Rate Mortgages and Other Consumer Loans
Consumer loans carry floors too, and the CFPB flags them as a cost worth pricing. Its guidance on what to look for in the fine print of an ARM puts it this way: "Some loans have a 'floor rate,' or a minimum rate. Even if the index goes lower, the rate on these loans does not adjust below the floor rate." It adds that floors, and clauses that let the rate adjust only upward, can make a loan more expensive and riskier, and suggests asking for quotes on comparable loans without them.
On most conforming ARMs the floor is the margin. Fannie Mae's Selling Guide section on ARMs states that "mortgage interest rates may never decrease to less than the ARM's margin, regardless of any downward interest rate cap," and caps the margin at 3.00 percentage points. So a SOFR ARM with a 2.75% margin cannot reset below 2.75%, even if SOFR fell to zero.
The CFPB's page on ARM rate caps describes the other side: an initial adjustment cap, commonly two or five percentage points; a subsequent cap, commonly one or two; and a lifetime cap, most commonly five. It notes that some loans have a different lifetime limit for decreases than for increases, "known as a floor." You don't have to hunt for these numbers. The Loan Estimate for an adjustable-rate loan carries an Adjustable Interest Rate (AIR) table on page 2 that lists the minimum and maximum interest rate the loan can reach after any introductory period, under 12 CFR 1026.37(j). A second table, for adjustable payments, appears only when the payment can change for reasons other than the rate, such as an interest-only period. How those limits change the ARM decision is covered in ARM vs. fixed.
Home equity lines of credit and variable-rate credit cards usually track the prime rate, which moved to 7.00% in September 2026 per the Fed's H.15 release, and some account agreements also set a minimum APR. When prime falls, a line with a minimum rate stops following it down. The account agreement is the only place that tells you, so read it before assuming a Fed cut will lower your bill. How prime rate changes reach your payments shows the pass-through.
From LIBOR to SOFR: Why Floors Went Quiet and Could Return
Floors were written for the world before 2022. For much of the 2010s short-term LIBOR sat near zero, and floors on floating-rate business loans were routine. The Fed's 2017 note observed that "the vast majority of loans breached their floors as the LIBOR rate reached 100 basis points in early January 2017," which tells you most of those floors had been set at or below 1.00%.
LIBOR has since been replaced. US dollar LIBOR stopped being published on a representative basis after June 30, 2023, and loans moved to SOFR, usually Term SOFR plus a credit spread adjustment for legacy deals. Floors carried over into SOFR documents. In the MaxLinear commitment above, the revolver's floor was 0.00% and the term loan's 0.50%; in any given deal the level is negotiated.
From 2023 to 2026, with SOFR between 3.50% and 5.40%, an index floor at the levels above was not binding. That stays true until short rates fall a long way, and the September 2026 hike moved them the other direction. A floor is insurance written against a scenario, and the scenario it covers, near-zero rates, was the actual state of the world from late 2008 to 2015 and again from 2020 to early 2022. It is not a hypothetical, which is why lenders keep asking for floors even when they cost borrowers nothing today.
How to Read and Negotiate a Floor
Before you sign a floating-rate loan, find four things in the note or credit agreement:
- What is floored. The benchmark (index floor) or the final rate (all-in floor). Search the definitions section for "Floor" and for "shall not be less than."
- The level against today's benchmark. Subtract the floor from the current benchmark. With SOFR at 3.87%, a 0.50% index floor is 3.37 points out of the money; a 4.00% all-in floor on a SOFR + 2.50% loan is 2.37 points away.
- Whether any hedge matches it. If you swap the loan to fixed, the swap needs the same floor or the hedge will leak in a low-rate year.
- What you get in exchange. A floor is worth something to the lender. If you accept one, ask for a lower margin, lower fees, or looser terms elsewhere.
For a lender or investor, the questions reverse. The protection a loan floor gives you is only as good as the borrower's ability to pay in a year when rates are low because the economy is weak, and it ends the day the borrower refinances. Hedging falling rates on a whole portfolio is usually done with purchased floors or with swaps, and it is a job for a treasury team and dealer quotes, not a rule of thumb.
If you want to see how the rate itself moves a payment, the mortgage payment calculator will show the dollar change for any rate you enter, including the floor rate.
FAQ
What is an interest rate floor in simple terms?
It is a minimum interest rate. In a floating-rate loan the rate cannot fall below the floor even if the benchmark does, which protects the lender. As a derivative, a floor pays its buyer the difference between the strike and the benchmark, times the notional, whenever the benchmark is below the strike.
What is the difference between an interest rate cap and floor?
A cap is a maximum and protects the borrower from rising rates; a floor is a minimum and protects the lender or investor from falling rates. Buying a cap while selling a floor creates a collar, which keeps the rate inside a band.
Is a floor rate the same as a minimum rate?
In loans, yes. "Floor rate," "minimum rate," and "rate floor" all mean the lowest rate the contract will charge. Check whether it applies to the benchmark only or to the total rate, because an all-in floor binds far more often.
Does an interest rate floor matter when rates are high?
Not directly. With SOFR at 3.87% in September 2026, a 0.50% floor has no effect on what anyone pays. It matters when rates fall toward it, as they did in 2020 and 2021, and it can make refinancing or hedging more expensive in the meantime.
Can I get a loan without a floor?
Sometimes. Floors are negotiable terms, not legal requirements, and the CFPB suggests asking lenders to quote comparable ARMs without one. On commercial loans, a lender that insists on a floor may accept a lower margin in exchange; ask for both versions side by side.
Sources
- Board of Governors of the Federal Reserve System, Open Market Operations: federal funds target range history
- Board of Governors of the Federal Reserve System, Implementation Note issued September 16, 2026
- Board of Governors of the Federal Reserve System, H.15 Selected Interest Rates
- Federal Reserve FEDS Notes, The Potential Increase in Corporate Debt Interest Rate Payments from Changes in the Federal Funds Rate (November 2017)
- Office of the Comptroller of the Currency, Comptroller's Handbook: Interest Rate Risk
- Consumer Financial Protection Bureau, If I am considering an ARM, what should I look out for in the fine print?
- Consumer Financial Protection Bureau, What are rate caps with an ARM, and how do they work?
- Consumer Financial Protection Bureau, Loan Estimate explainer
- Regulation Z, 12 CFR 1026.37, Content of disclosures (Loan Estimate) — (i) Adjustable Payment table, (j) Adjustable Interest Rate table
- Fannie Mae, Selling Guide B2-1.4-02, Adjustable-Rate Mortgages
- U.S. Securities and Exchange Commission (EDGAR), MaxLinear, Inc. commitment letter, Exhibit 10.1, May 2022
- Federal Reserve Bank of St. Louis, FRED: Secured Overnight Financing Rate (SOFR), data originally published by the Federal Reserve Bank of New York
 Next entry · No. 2,444Understanding Interest Rate Futures: A Comprehensive Guide for Institutional Investors
See also
-
 No. 2,798
05 Feb 2025
20 min
Understanding Lease Payments: An In-Depth Guide for Institutional Investors
Business Finance
-
 No. 2,589
19 Jan 2025
18 min
The Unauthorized Trades of Jérôme Kerviel: A Rogue Trader Case Study
Business Finance
-
No. 2,444
07 Jan 2025
19 min
Understanding Interest Rate Futures: A Comprehensive Guide for Institutional Investors
Business Finance
-
 No. 5,755
05 Oct 2025
20 min
Understanding Wire Transfers: A Comprehensive Guide for Institutional Investors
Business Finance
-
 No. 4,862
23 Jul 2025
24 min
Maximizing Your Investment Returns: A Comprehensive Guide to Tax Breaks for Professional and Institutional Investors
Business Finance
-
 No. 4,420
17 Jun 2025
22 min
Understanding Restrictive Covenants: A Comprehensive Guide for Institutional Investors
Business Finance