Gamma Hedging in Options Trading: How It Works, With the Numbers
Gamma hedging adds options so a delta hedge stops going stale. A hedged short call lost $615 on a 5% move; made gamma-neutral, it lost about $2.
Gamma hedging in options trading means adding or removing options so that your position's delta stays put when the underlying price moves. A plain delta hedge with stock or futures only works for the price at which you set it; gamma is the reason it goes stale, and a gamma hedge is the fix. You pay for that fix, usually by giving up the time-decay income that made the short-option position attractive in the first place.
The rest of this page shows why, with numbers you can check: a delta-hedged short call that loses $615 on a 5% move, the same position made gamma-neutral losing about $2, and a bitcoin version where the moves are bigger and the market never closes. Scope honesty first: this is general information built on stated assumptions (Black-Scholes pricing, no dividends, a zero interest rate for simplicity), not trading advice. Options can lose more than you put in, and your broker has to approve your account for each strategy level before you can use it.
What Gamma Measures, and Why a Delta Hedge Goes Stale
FINRA's options guide for investors defines the two Greeks that matter here. Delta is "the amount an option price is expected to change based on a $1 change in the underlying stock." Gamma is "the rate of change in an option's delta based on a $1 change in the price of the underlying security." Delta is the speed; gamma is the acceleration.
That definition explains the whole topic. Suppose you sell a call with a delta of 0.51 and buy 51 shares per contract to offset it. You are now delta-neutral, but only at today's price. If the stock rises, the call's delta climbs toward 1.00 and your 51 shares no longer cover it. If the stock falls, the delta sinks toward zero and you are holding too many shares. Either way, the hedge you set this morning is wrong by the afternoon, and the size of that error is set by gamma. There is a longer walk-through of the first Greek in the entry on delta in options trading.
Three facts about gamma drive every hedging decision:
- Gamma is highest at the money. An option whose strike is near the current price has the most uncertain outcome, so its delta swings fastest.
- Gamma rises sharply as expiration approaches for at-the-money options, and collapses toward zero for options that are clearly in or out of the money.
- Buyers of options are long gamma; sellers are short gamma. Long gamma means your delta moves in your favour as the price moves. Short gamma means it moves against you.
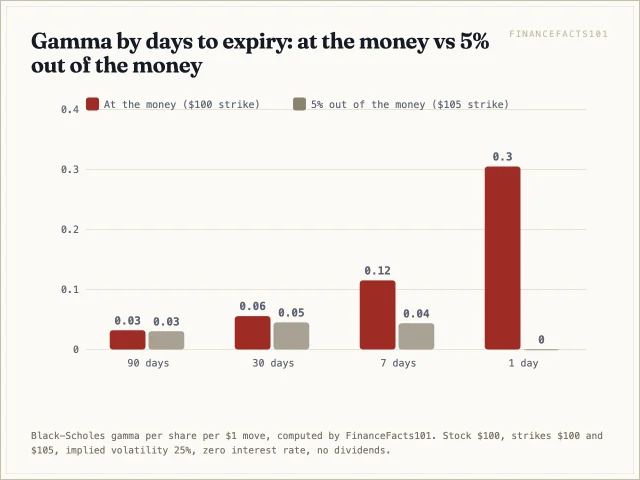
The chart makes the second point concrete. With the stock at $100 and implied volatility at 25%, an at-the-money option's gamma roughly doubles between 30 days and 7 days to expiry, then nearly triples again on the final day. A 5%-out-of-the-money option does the opposite: its gamma is almost gone on the last day because it is almost certainly expiring worthless. This is why gamma risk in options is concentrated in short-dated, near-the-money contracts, and why same-day (0DTE) options get so much attention.
Gamma Risk: Long Gamma vs Short Gamma
"Gamma risk" is the risk that a large move makes your delta hedge wrong faster than you can fix it. Who carries it depends on which side of the option you are on.
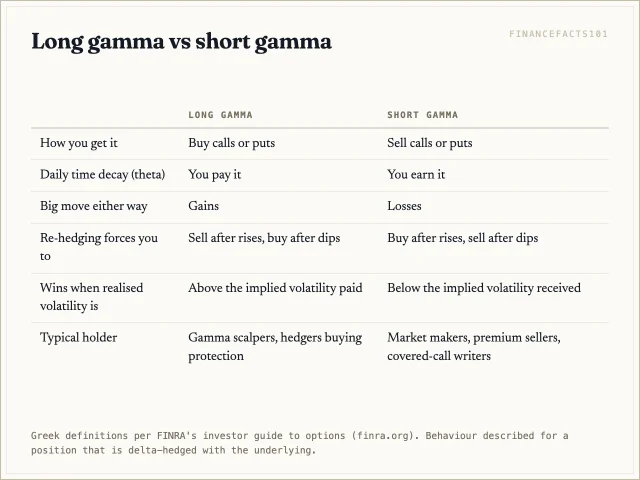
If you are long gamma (you bought options), you are rarely hurt by a big move: after a rally your delta rises, so you are longer into strength; after a drop it falls, so you are shorter into weakness. You pay for that in theta, the daily time decay the entry on theta covers in detail.
If you are short gamma (you sold options), you collect theta every day the market sits still, and you lose when it moves a lot in either direction. Market makers who sell options to the public, and retail traders who sell covered calls, cash-secured puts or iron condors, are all short gamma to some degree. FINRA's guide lists the practical side of this: assignment risk, pin risk near expiry, and margin calls that can arrive at the worst moment.
A Delta-Hedged Short Call, Worked Through
Here is the problem gamma hedging solves, in dollars. Assumptions: the stock trades at $100, you sell 10 at-the-money calls (strike $100, 30 days to expiry, 1,000 shares of exposure) at an implied volatility of 25%, with no dividends and a zero interest rate. Black-Scholes prices each call at $2.86, so you collect $2,859.
Each call has a delta of 0.514, so you buy 514 shares to be delta-neutral. Your position's gamma is about −55.6: for every $1 the stock moves, your net delta moves 55.6 shares against you. Your theta is about +$48 a day, the income for carrying that risk.
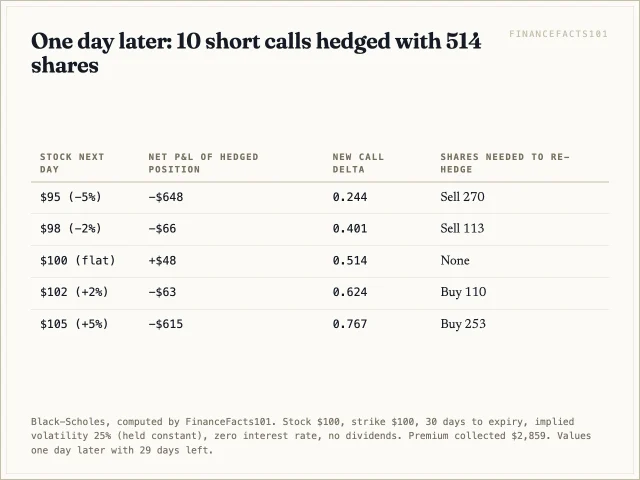
On a quiet day you keep the $48. On a $2 day you lose about $65. On a $5 day you lose around $615 to $648, more than twelve days of theta gone in one session. A quick rule of thumb gets you close: the loss from gamma is about ½ × gamma × (move)², so ½ × 55.6 × 5² = $695, minus the day's $48 of theta, or about $647. (The exact figure differs a little because gamma itself changes as the stock moves.)
The same arithmetic gives the break-even move. Setting ½ × 55.6 × move² equal to $48 gives about $1.31, or 1.31% of the stock price. That is no coincidence: 25% annual volatility divided by the square root of 365 days is 1.31%. A delta-hedged short option makes money on days when the stock moves less than implied volatility says it should, and loses on days it moves more. Gamma hedging exists because traders do not always want that bet.
After the $5 rally the call's delta is 0.767, so to be neutral again you must buy 253 more shares at $105. After the $5 drop the delta is 0.244, so you sell 270 shares at $95. Short gamma forces you to buy after rises and sell after falls, which is where the loss comes from.
How a Gamma Hedging Strategy Works, Step by Step
Stock cannot fix gamma. Its delta is always exactly 1 per share and its gamma is zero, so no amount of buying or selling shares changes how fast your delta moves. The only instruments with gamma are options, so a gamma hedge always means trading options.
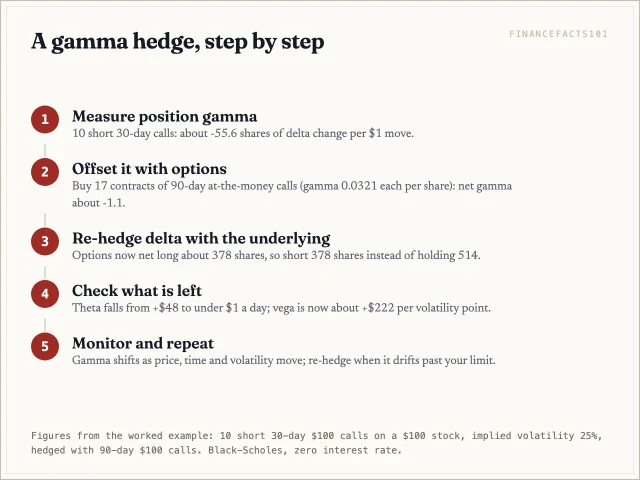
Using the worked example: your 10 short 30-day calls carry about −55.6 of gamma. A 90-day at-the-money call on the same stock has gamma of 0.0321 per share, so buying 17 contracts (1,700 shares' worth) adds about +54.6 and leaves net gamma near −1.1. Those 17 calls cost $4.95 each per share, $8,414 in all.
The new calls also carry delta, about +892 shares' worth. Combined with the −514 from the short calls, the options now make you net long about 378 shares, so the stock leg flips: instead of owning 514 shares, you short 378. You are now delta-neutral and gamma-neutral at the same time.
Re-run the $5 move. Up or down, the position now loses about $1 to $2 instead of $615 to $648. The hedge worked. Now look at what it cost:
- Theta is gone. Net time decay is under $1 a day. The long 90-day calls bleed almost exactly what the short 30-day calls earned, because at the same implied volatility, gamma and theta are two sides of one trade. You cannot keep the income and remove the risk.
- You now have vega. The position gains or loses about $222 for every one-point change in implied volatility. You swapped exposure to price moves for exposure to volatility changes.
- You pay spreads twice, on the 17 calls you bought and on the 378 shares you shorted.
That trade-off is the honest answer to "is gamma hedging worth it?" A market maker who must stay in business through a crash usually says yes for a large part of the book. A retail trader selling premium for income is usually running short gamma on purpose, and the relevant decisions are position size and where to cut losses, not full neutralisation.
Gamma Hedging vs Delta Hedging, and Gamma Scalping
Delta hedging neutralises the first-order price exposure with the underlying (shares, futures or perpetual swaps). It is cheap and it has to be redone as the price moves. Gamma hedging neutralises the second-order exposure with other options, so the delta hedge needs redoing less often. Most professional books do both: gamma and vega are managed with options across strikes and expiries, and the leftover delta is cleaned up with the underlying several times a day.
A gamma trading strategy, often called gamma scalping, runs the logic in reverse. You buy options (long gamma), delta-hedge them, and re-hedge after moves: sell shares after a rally, buy after a dip. Each re-hedge locks in a small gain, and you win if those gains exceed the theta you pay. In the example above, a long-gamma trader holding the other side would have made roughly $615 to $648 on the $5 day and lost $48 on the quiet day. Gamma scalping is, in effect, a bet that realised volatility will exceed the implied volatility you paid, the mirror image of the short-gamma position.
Gamma Hedging in Crypto Options
The mechanics are identical in crypto. What changes is the scale of the moves, the hours, and the hedging instruments.
The venues. Deribit, the crypto derivatives exchange that Coinbase completed its purchase of in August 2025, says in its own options primer that all its options are European style (exercisable only at expiry) and cash settled. Its standard bitcoin options have a contract multiplier of 1 BTC, per the Deribit venue specification published by the trading network Paradigm. In the United States, listed options on spot bitcoin ETFs arrived after the SEC approved Nasdaq ISE's rule change for options on the iShares Bitcoin Trust on September 20, 2024. Those are standard 100-share equity options with regular trading hours.
The worked example. Assume bitcoin at $100,000 (an assumption for arithmetic, not a forecast), a 7-day at-the-money call, and implied volatility of 50%. Each call is worth about $2,762, has a delta of 0.514, and loses about $197 a day to time decay. Sell 10 of them, hedge with 5.14 BTC long, and you collect about $2,000 a day in time decay ($2,048 over the next day in the table below, slightly more than the $197-per-call rate because decay speeds up near expiry). The break-even daily move is about $2,617, or 2.62%, which is 50% divided by the square root of 365.
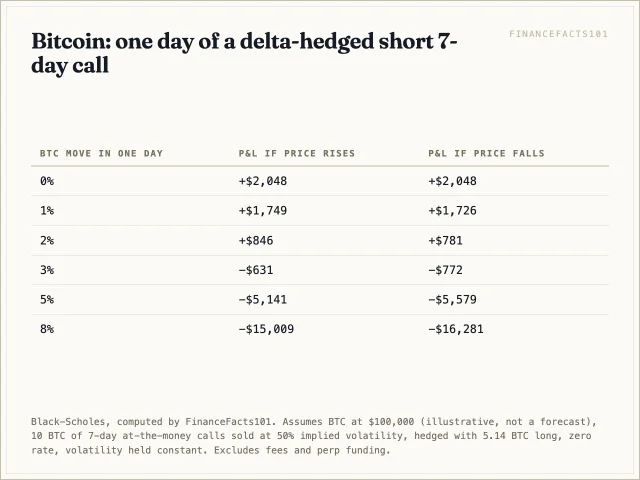
A 2% move leaves you ahead. A 3% move puts you behind. A 5% move costs $5,141 to $5,579, nearly three days of income, and an 8% move costs $15,000 to $16,000. Bitcoin moves of that size are not rare, which is why short-dated crypto options sellers watch gamma closely.
What is different from equities:
- No closing bell. Crypto trades 24/7, including weekends, so there is no overnight gap to plan around, but there is also no pause in which the risk stops. Theta accrues every calendar day.
- Hedging with perpetual futures. Most crypto desks hedge delta with perpetual swaps rather than spot. Perps have no expiry and no gamma of their own, but longs and shorts exchange periodic funding payments, so a hedge held for weeks carries a funding cost (or credit) on top of trading fees.
- Inverse contracts. Some crypto options are margined and settled in the coin itself, so your collateral's dollar value moves with the underlying. That adds a delta of its own that a dollar-based hedge has to account for. Check your venue's contract specification before assuming the equity math carries over unchanged.
Gamma Drain: Rebalancing Loss and Hedging Frequency
Traders who hedge short options with perps often describe the ongoing cost as "gamma drain" or "rebalancing loss." It is the buy-high, sell-low pattern from the equity example: every re-hedge of a short-gamma position happens after the price has moved against you, and each one realises a loss of roughly ½ × gamma × (move)².
Hedging more often does not make that expected loss go away. In the textbook model, the expected cost of hedging a short option depends on how much the price actually moves (realised volatility), not on how often you rebalance. What rebalancing frequency changes is how uneven the outcome is. The tracking error of the hedge shrinks roughly with the square root of the number of rebalances: hedge four times as often and the spread of outcomes roughly halves, while your trading costs roughly quadruple.
Path matters in any single case. In the bitcoin example, a 5% rally hedged once at the end of the day cost $5,141. Re-hedging halfway, at +2.5%, cut that to about $1,569, because the second half of the move hit a corrected hedge. Had the price reversed after the first 2.5% instead, that same mid-day re-hedge would have locked in a loss the market was about to give back.
So the practical choice of hedging frequency comes down to three costs weighed against each other:
- Trading costs per rebalance: exchange fees, the bid-ask spread on the perp, and slippage in fast markets.
- Funding on the perp hedge, paid or received for as long as the hedge is open.
- Risk tolerance: how large a one-day loss the book can take before rebalancing.
Common approaches are rebalancing on a fixed schedule, rebalancing when delta drifts past a band (for example, whenever net delta exceeds a set number of coins), or both. Wider bands mean fewer trades and a bumpier profit and loss. None of them change the fact that a short-gamma book is paid to absorb realised volatility.
When Dealer Gamma Moves Markets
When market makers are collectively short gamma in a stock, their hedging can push the price further in the direction it is already moving: they buy after rises and sell after falls. The popular name for the upside version is a gamma squeeze.
It is easy to over-apply. In its staff report on equity and options market structure in early 2021, the SEC looked for exactly this in GameStop and did not find it.
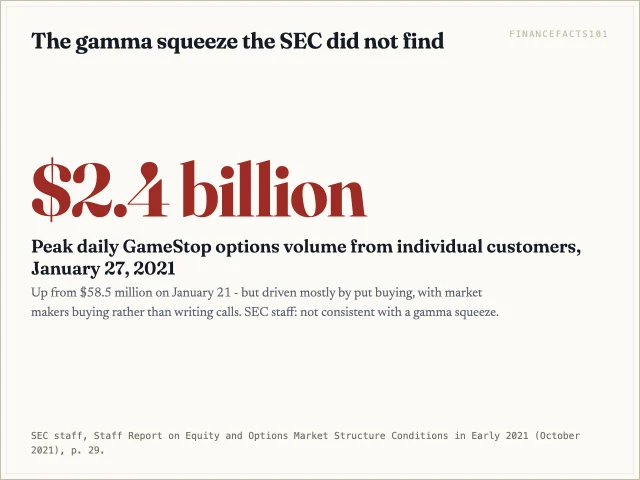
Staff found that individual customers' GameStop options volume rose from $58.5 million on January 21, 2021 to a peak of $2.4 billion on January 27, but that the increase was driven mostly by put buying, and that market makers were buying, not writing, call options, which "by themselves are not consistent with a gamma squeeze." Dealer gamma is real, but it is one force among several, and a price spike alone is not evidence of it.
The rise of same-day expiry options has kept the question alive, because 0DTE contracts carry the highest gamma there is. In the Federal Reserve's September 2023 Senior Credit Officer Opinion Survey, about half of the responding dealers (10 of 21) reported clients actively trading 0DTE options, and two-fifths said they do not collect margin on those trades.
Where Gamma Shows Up on Your Platform
Gamma belongs to options, not to futures. A futures contract, whether a CME contract reached through a retail futures platform such as AvaFutures (which AvaTrade launched in June 2024 to offer CME Group futures) or a crypto perpetual, has a delta of roughly 1 per unit and no gamma. That makes futures the natural tool for the delta leg of a hedge and useless for the gamma leg.
If you trade options, your platform's position or risk view is where you will find position-level Greeks, if it shows them at all; which Greeks are reported varies by broker and platform. Two checks before trusting the number: whether gamma is shown per share, per contract or for the whole position, and whether it is quoted per $1 move or per 1% move. The ten calls in the worked example show a gamma of 0.0556 per share, 5.56 per contract and 55.6 for the position, all the same exposure. On bitcoin at $100,000 the per-$1 and per-1% conventions differ by a factor of 1,000.
Risks and Limits of Gamma Hedging
- Model risk. Every Greek here comes from a pricing model. Real volatility changes, and gamma calculated at one implied volatility is wrong at another.
- Gaps and jumps. No hedge rebalanced after the fact protects you from a price that jumps overnight or on news. Stock markets gap between sessions; crypto can move 10% in minutes.
- Liquidity. The options needed for a gamma hedge may be wide or thin when you need them most.
- Costs compound. Each re-hedge pays a spread. A position that looks profitable on theta can lose money after trading costs.
- You do not end up risk-free. Neutralising delta and gamma leaves vega, and the concept of a hedged portfolio earning the risk-free rate, covered in the entry on risk-neutral pricing, only holds in the model.
Before trading options at all, the SEC's introduction to options and the Characteristics and Risks of Standardized Options disclosure your broker provides are the required reading.
FAQ
What is the difference between delta hedging and gamma hedging?
Delta hedging offsets how much your position gains or loses on a small price move, and it is done with the underlying asset (shares, futures or perps). Gamma hedging offsets how fast that delta changes, and it can only be done with options, because the underlying has no gamma. Delta hedging must be redone after every significant move; gamma hedging makes those adjustments smaller and less frequent, at the cost of time-decay income and new exposure to implied volatility.
Is gamma hedging profitable?
Not by itself. It is insurance, not a return source. A gamma-neutral position gives up most of its theta income, as the worked example shows (from $48 a day to under $1). Traders who profit from gamma do so by taking a view: long gamma (gamma scalping) wins if realised volatility exceeds the implied volatility paid; short gamma wins if it comes in lower.
Why is gamma highest near expiration?
Close to expiry, an at-the-money option's outcome flips between worthless and in the money on small price changes, so its delta jumps between near 0 and near 1. In the example on this page, an at-the-money option's gamma goes from 0.056 at 30 days to 0.305 on the final day. Options well away from the money show the reverse, because their outcome is already nearly settled.
How often should you rebalance a delta hedge on crypto options?
There is no single right frequency. Rebalancing more often reduces how far results can stray from the expected outcome but does not reduce the expected cost of carrying short gamma, and every rebalance adds fees, spread and potentially funding on the perp hedge. Many desks rebalance when net delta drifts past a set band rather than on a fixed clock, and widen the band when trading costs are high.
Sources
- FINRA, Options — definitions of delta, gamma, theta and vega; options account approval levels; assignment, pin and margin risk
- SEC Office of Investor Education and Advocacy, An Introduction to Options – Investor Bulletin
- SEC staff, Staff Report on Equity and Options Market Structure Conditions in Early 2021, October 2021 — GameStop options volume and the finding of no gamma squeeze (report p. 29)
- SEC, Release No. 34-101128, order approving options on the iShares Bitcoin Trust on Nasdaq ISE, September 20, 2024
- Federal Reserve Board, Senior Credit Officer Opinion Survey on Dealer Financing Terms, September 2023 — special questions on 0DTE options
- Deribit Insights, What is an options contract? — all Deribit options are European style and cash settled
- Paradigm, Deribit venue specification — BTC options contract multiplier 1 BTC
- AvaTrade, Step Into the Future of Trading With AvaFutures, Powered by AvaTrade, June 20, 2024 — AvaFutures launch, CME Group futures
- Coinbase, Deribit Joins Coinbase, August 2025 — completion of the Deribit acquisition
- Worked examples: Black-Scholes values computed by FinanceFacts101 from the stated inputs (no dividends, zero interest rate, implied volatility held constant over the one-day horizon)
 Next entry · No. 1,733Understanding Gamma Neutral Strategies: Achieving Delta and Volatility Hedging in Options Trading
See also
-
 No. 2,477
09 Jan 2025
21 min
Understanding In-The-Money (ITM) Options: Maximizing Profits in Finance
Business Finance
-
 No. 1,166
06 Aug 2024
21 min
Understanding Early Exercise: Benefits, Advantages and Strategies for Options Trading and Employee Stock Options
Business Finance
-
 No. 4,953
30 Jul 2025
23 min
Understanding Theta: The Rate of Decline in Option Value with Time
Finance Policy
-
 No. 962
08 Jul 2024
20 min
Understanding Delta: A Key Concept for Options Trading
Financial Education
-
 No. 5,880
15 Oct 2025
23 min
Understanding Zacks Lifecycle Indices: A Comprehensive Guide for Professional and Institutional Investors
Business Finance
-
 No. 5,861
14 Oct 2025
18 min
Understanding Yield Curves: Normal, Inverted, and Flat – Predictors of Economic Transitions
Business Finance