Household Income: Meaning, Definition and How to Calculate It

Household income is the pre-tax income of everyone in a home, related or not. US median: $87,460 in 2025. How it differs from family and per capita income.
Household income is the combined income of everyone who lives in the same home, whether or not they are related. In the US Census Bureau's official statistics it means the pre-tax cash income of every household member aged 15 and older, added together over a year. Wages, self-employment earnings, Social Security, pensions, interest and rent all count; noncash benefits and capital gains do not.
The typical US household had an income of $87,460 in 2025, according to the Census Bureau's Income in the United States: 2025, released September 15, 2026. That figure is a median: half of households had more, half less. This page explains what household income means, how it differs from family income and per capita income, how to calculate yours, and why a credit card application or a health insurance form may define it differently. It is general information, not tax or lending advice.
What Household Income Means
The meaning starts with the word "household." The Census Bureau's Current Population Survey definitions say "a household consists of all the people who occupy a housing unit," meaning a house, apartment or room used as separate living quarters. It "includes the related family members and all the unrelated people, if any, such as lodgers, foster children, wards, or employees who share the housing unit." A person living alone is a household. So is a group of roommates. People in institutions such as prisons and nursing homes are outside the survey altogether, and people in other group quarters are not counted in households. College students living in dorms are counted in their parents' household when the parents report them; the Census Bureau's 2025 income report (Appendix B) says dorm students "are included in the estimates only if information about them is reported in an interview at their parents' home."
Household income is then the total income of those people. The survey asks about income "for each person in the sample 15 years old and over," and adds it up by household. Children under 15 are household members but are not asked about income.
Three features of the official definition matter most:
- It is gross, not take-home. Money income is counted "before payments for personal income taxes, social security, union dues, medicare deductions, etc." Your paycheck deposit is smaller than your household income.
- It is annual. "Annual household income" means income received over a full year; the Census survey asks about the previous calendar year.
- It follows who lives there now. Income of someone who moved out before the interview is left out. Income of someone who moved in is included, even if it was earned before they arrived.
Each household also has one householder: the person "in whose name the housing unit is owned or rented," to whom everyone else's relationship is recorded. Census tables that sort households by age, race or education use the householder's characteristics.
What Counts as Household Income, and What Doesn't
The Census Bureau counts 18 sources of money income. The appendix to its 2025 income report lists them: earnings; unemployment compensation; workers' compensation; Social Security; Supplemental Security Income; public assistance; veterans' payments; survivor benefits; disability benefits; pension or retirement income; interest; dividends; rents, royalties, and estates and trusts; educational assistance; alimony; child support; financial assistance from outside the household; and other income.
The same appendix spells out what is left out. Money income excludes "certain money receipts such as capital gains," and "also excludes tax credits such as the Earned Income Tax Credit (EITC)." It "does not reflect that some families receive noncash benefits such as nutritional assistance, health benefits, and subsidized housing," nor employer payments toward retirement plans or health coverage.
In practice that means:
- Count gross wages, salary, tips, bonuses and commissions; net earnings from a business or freelance work; Social Security and pension checks; interest, dividends and rental income; and cash support such as alimony or child support.
- Leave out gains from selling stock or a house, SNAP benefits, Medicaid, housing vouchers, tax refunds and credits, and your employer's 401(k) match.
Because these rules are the Census Bureau's, other forms can differ. The last sections of this page show how.
Household Income vs Family Income vs Per Capita Income
These three measures divide the same money in different ways.
Family income counts only people related to the householder. The Census Bureau defines a family as "a group of two people or more (one of whom is the householder) related by birth, marriage, or adoption and residing together." A lodger or an unmarried roommate is in the household but not the family, so family income can be lower than household income in the same home. A person living alone has household income but no family income, because a family needs two or more related people.
Per capita income divides total income by every person, children included. The Census definition: "the average income computed for every man, woman, and child in a particular group," found by dividing the group's total income by its population. It describes a population, such as a country, state or city, rather than a single household. The site's entry on per capita income covers its uses and limits.
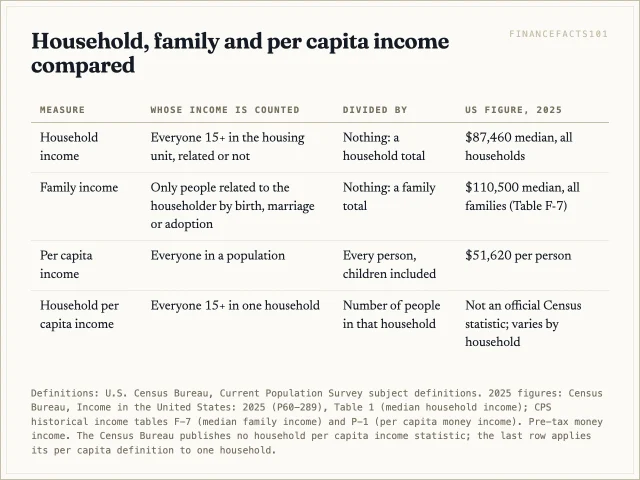
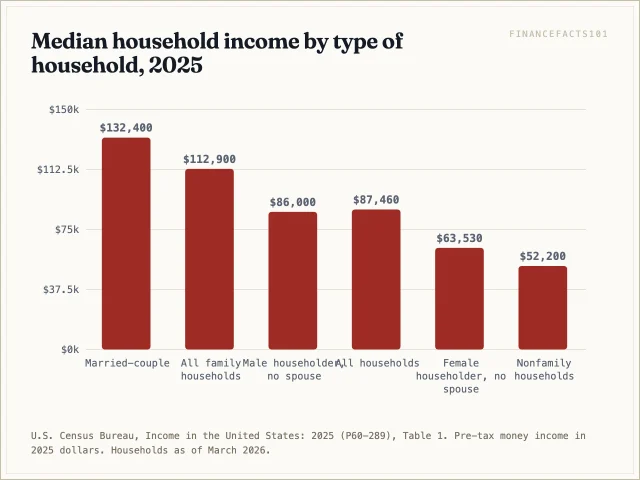
The national figures show why the measure matters. For 2025, the median household income was $87,460. The median household income of family households was $112,900, and of married-couple households $132,400; median family income, which counts only related members, was $110,500, per the Census Bureau's historical income Table F-7. The Census Bureau's per capita money income, which divides by all 338.6 million people in the survey's population, was $51,620. Same economy, same year, very different numbers.
The gap between the all-household and family-household medians has a simple cause. Of 137.1 million households in 2025, 49.1 million were nonfamily households, people living alone or only with unrelated people, and their median income was $52,200. Take them out and the typical figure rises.
Household Per Capita Income: What It Means
Household per capita income is household income divided by the number of people in the household, children included. It turns a household total into an income per person, which makes a single earner and a family of five comparable. The Census Bureau does not publish a "household per capita income" statistic; the term simply applies its per capita definition to a single household.
- A single person earning $60,000: household income $60,000, household per capita income $60,000.
- A family of four with $120,000: household income $120,000, household per capita income $30,000.
By household income, the family looks twice as well off. Per person, it has half as much. That is why some poverty research ranks households by income per person rather than by the total.
Two cautions. First, do not confuse this household figure with a country's "per capita income," which divides the whole population's income by the whole population. Second, dividing by headcount overstates what larger households need, because two people can share one rent and one refrigerator. Statistical agencies often use "equivalence scales" that count additional members at less than one full person; the Census Bureau's 2025 report includes equivalence-adjusted income measures in its inequality tables.
How to Calculate Your Household Income: A Worked Example
Consider one hypothetical household of six people sharing a rented house in 2025:
- Parent A, 42: salary of $78,000 before taxes and payroll deductions.
- Parent B, 40: freelance designer, $31,000 of net self-employment income after business expenses.
- Daughter, 17: summer job paying $4,200.
- Son, 9: no income.
- Grandmother, 71: Social Security of $1,900 a month ($22,800 a year) plus $1,300 of interest from a savings account.
- Lodger, 29, unrelated and renting a room: $46,000 salary.

Household income counts everyone 15 and older who lives there: $78,000 + $31,000 + $4,200 + $22,800 + $1,300 + $46,000 = $183,300. The daughter counts because she is 15 or older; the son does not report income. The lodger counts because household income ignores relationships.
Family income drops the lodger: $183,300 − $46,000 = $137,300.
Household per capita income divides by all six people: $183,300 ÷ 6 = $30,550. Per family member it is $137,300 ÷ 5 = $27,460.
None of these is take-home pay. After federal and state income taxes and payroll taxes, the spendable amount is considerably smaller; the take-home pay calculator estimates the difference for a single salary.
Median vs Average Household Income
The Census Bureau publishes both, and they tell different stories. Median income "divides the income distribution into two equal groups, half having incomes above the median, half having incomes below." Mean (average) income is total income divided by the number of households.
For 2025, per the Census Bureau's income tables:
- Median household income: $87,460 (margin of error ±$1,040)
- Mean household income: $126,700
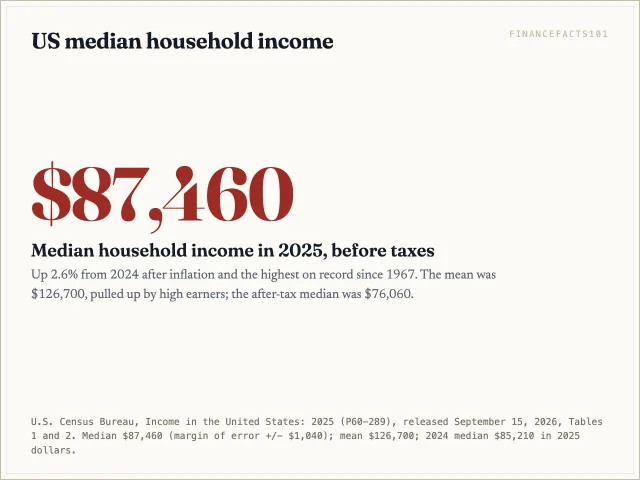
The mean is about $39,000 higher because high incomes pull an average up and have no effect on a median. In 2025, 17.2% of households had income of $200,000 or more, while 6.9% had under $15,000. For "what does a typical household earn," the median is the better answer.
Some other 2025 medians from Table 1 of the report, all pre-tax:
- By region: West $97,440; Northeast $95,110; Midwest $85,820; South $80,690.
- By age of householder: highest at 45 to 54 ($120,100); $59,680 at 65 and older, when many households live on Social Security and pensions.
- By education of householder (25 and older): $138,300 with a bachelor's degree or more; $37,090 without a high school diploma.
The 2025 median was up 2.6% from $85,210 in 2024 after adjusting for inflation, and it was the highest on record in data going back to 1967, according to the Census Bureau's September 15, 2026 release. The after-tax median was $76,060.
Where Household Income Shows Up, and Which Definition Applies
Many readers meet the term on a form. The answer to "whose income goes in the box" depends on who is asking, and the rules can be stricter than the Census version.
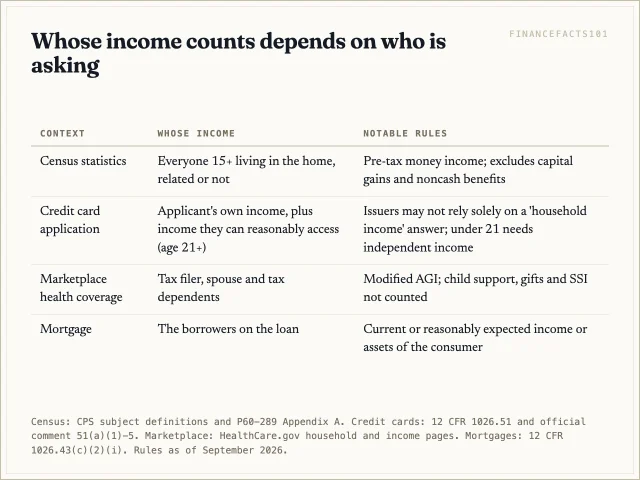
Credit card applications. Federal rules require card issuers to consider your ability to pay from "income or assets." Under 12 CFR 1026.51, an applicant 21 or older may include income they have "a reasonable expectation of access" to, such as a spouse's pay deposited regularly into a joint account. The CFPB's official interpretation adds that "card issuers may not rely solely on information provided in response to a request for 'household income'" and would need more information about the applicant's income, including income they can reasonably access. Under 21, the rule looks for your own independent income, or a cosigner or joint applicant who is 21 or older. A roommate's salary that you have no access to does not count.
Health insurance through the Marketplace. HealthCare.gov counts a tax household, which "usually includes the tax filer, their spouse if they have one, and their tax dependents." Roommates are out, and an unmarried partner is included only if you have a child together or claim the partner as a dependent. Income is modified adjusted gross income, and the Marketplace's income rules exclude child support and Supplemental Security Income, both of which the Census counts, as well as gifts and loan proceeds. A dependent teenager's summer-job pay counts only if she has to file a federal tax return.
Mortgages and other loans. Lenders qualify the people who will owe the debt. The ability-to-repay rule at 12 CFR 1026.43 requires a mortgage lender to consider "the consumer's current or reasonably expected income or assets," not the income of everyone under the roof. In general, income from a relative who is not on the loan does not count toward qualifying, though some loan programs make limited exceptions. The guide to how much house you can afford shows how lenders turn that income into a debt-to-income limit.
In the worked example above, the Census figure is $183,300. Either parent's credit card application could include the other's pay if they share access to it, as through a joint account, but not the lodger's. On a Marketplace application, the tax household is the couple and their two children, assuming the grandmother files her own return and is not claimed as a dependent; she and the lodger are separate.
What Household Income Leaves Out
Household income is a useful headline number with known blind spots:
- Taxes. It is pre-tax. The gap between the $87,460 median and the $76,060 after-tax median reflects federal and state income taxes and payroll taxes, net of tax credits.
- Household size. A $90,000 household of one and of six are counted the same; per capita or equivalence-adjusted figures fix that.
- Noncash help. SNAP, Medicaid and housing assistance raise living standards without appearing in money income.
- Wealth and debt. Two households with equal income can have very different savings and obligations; the entry on net worth covers that side.
- Local costs. The same income stretches further in some regions than others, which regional medians only partly show.
FAQ
What does household income mean?
Household income means the total income of everyone living in the same home, related or not. In US Census statistics it is the pre-tax money income of each member aged 15 and older, added together for a year. It includes wages, self-employment income, Social Security, pensions, interest, dividends and rent, and excludes capital gains and noncash benefits.
Is household income before or after taxes?
Before. Census household income and most application forms mean gross income, before income taxes, Social Security and Medicare deductions. The US median was $87,460 before taxes in 2025 and $76,060 after taxes.
Does household income include my roommate or partner?
For Census statistics, yes: everyone living in the housing unit counts, including roommates and unmarried partners. For a credit card, count only income you have a reasonable expectation of access to, which usually excludes a roommate's pay. For Marketplace health coverage, count your tax household: you, your spouse and your tax dependents.
What is household per capita income?
Household per capita income is household income divided by the number of people in the household, children included. A family of four with $120,000 has household per capita income of $30,000. It differs from a country's per capita income, which divides total income by the whole population; the US figure was $51,620 in 2025.
Sources
- U.S. Census Bureau, Income in the United States: 2025 (P60-289, September 15, 2026; PDF) — median household income $87,460; money income definition, 18 income sources and exclusions (Appendix A); householder definition; group quarters (endnote 6); institutions and dorm students (Appendix B)
- U.S. Census Bureau, Table 1: Income Summary Measures by Selected Characteristics, 2024 and 2025 — medians by household type, region, age and education
- U.S. Census Bureau, Table 2: Households by Total Money Income, 1967 to 2025 — mean household income $126,700; income distribution
- U.S. Census Bureau, CPS historical income tables, Table F-7: Median and Mean Family Income of All Families by Type of Family, 1947 to 2025 — median family income $110,500 in 2025
- U.S. Census Bureau, CPS historical income tables, Table P-1: Per Capita Income, All People, 1967 to 2025 — per capita money income $51,620 in 2025
- U.S. Census Bureau, Income, Poverty and Health Insurance Coverage in the United States: 2025 (press release) — 2.6% increase, highest on record since 1967; post-tax median $76,060
- U.S. Census Bureau, Current Population Survey subject definitions — household, family, householder, income measurement, median, mean and per capita income
- Electronic Code of Federal Regulations, 12 CFR 1026.51 and Supplement I to Part 1026 (comment 51(a)(1)-5) — ability to pay for credit cards; "household income" requests
- Electronic Code of Federal Regulations, 12 CFR 1026.43 — mortgage ability-to-repay income requirement
- HealthCare.gov, Who's included in your household and What's included as income — Marketplace tax household, MAGI and excluded income types
 Next entry · No. 2,227Understanding House Maintenance Requirements in Margin Trading
See also
-
 No. 702
24 May 2024
21 min
Understanding Cost-of-Living Adjustments (COLAs): How Inflation Impacts Your Social Security Benefits
Financial Tools
-
 No. 5,587
21 Sep 2025
20 min
Understanding Walk-Away Leases: Pros, Cons, and Alternatives for Professional Investors
Business Finance
-
 No. 5,530
16 Sep 2025
20 min
Understanding Voluntary Bankruptcy: The Proactive Approach to Debt Relief for Corporations and Individuals
Business Finance
-
 No. 5,220
21 Aug 2025
20 min
Understanding Unearned Discounts in Finance and Investment: What They Are, How to Calculate Them, and Their Significance
Business Finance
-
 No. 4,770
15 Jul 2025
14 min
Stop Payment on a Check: The Request Procedure, Rules and Fees
Business Finance
-
 No. 4,469
21 Jun 2025
22 min
Revolving Credit: Understanding the Flexible Financial Tool for Institutional and Professional Investors
Business Finance