Lloyd's of London: What It Is and How the Insurance Market Works

Lloyd's of London is a marketplace, not an insurer: its syndicates wrote £57.9bn of premium in 2025. How it works, who the members are, how claims get paid.
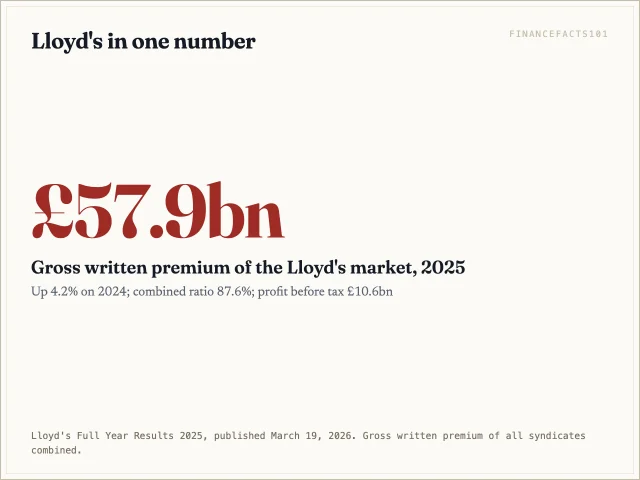
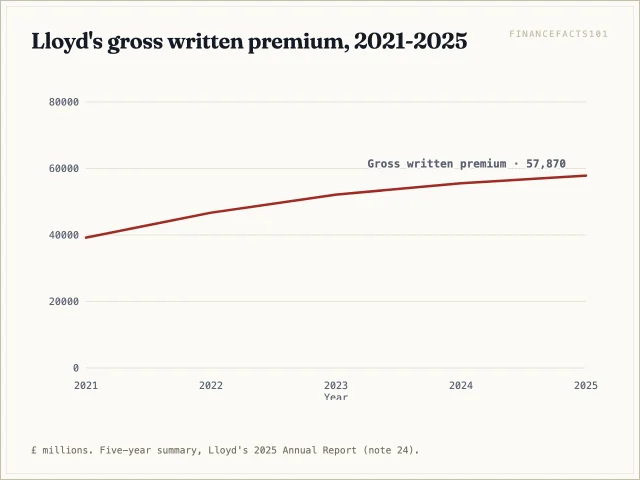
Lloyd's of London is an insurance marketplace, not an insurance company. Lloyd's itself does not take on your risk. It runs the building, the rules and a shared safety net, and the insuring is done by about a hundred competing businesses called syndicates, each backed by capital from its members. Brokers bring risks to those syndicates, often large, unusual or hard-to-place ones such as oil rigs, aircraft, ship cargo, cyber attacks and catastrophe reinsurance, and one or several syndicates agree to cover them. In 2025 the syndicates together wrote £57.9 billion of gross premium, according to Lloyd's full-year results.
This page explains what Lloyd's of London is, how the Lloyd's insurance market works from broker to claim, who does what inside it, the "chain of security" that stands behind every policy, what Lloyd's insures and how you can buy it in the United States, who the members are and how people invest, and a short history, including the 1990s crisis that reshaped it. Figures are the latest Lloyd's has published, as of September 2026.
What Is Lloyd's of London?
The legal entity is the Society of Lloyd's, and its governance structure and rules are set by the Lloyd's Act 1982, according to Lloyd's governance page. The Society has two sides that people often blur together:
- The Lloyd's market: the syndicates, the managing agents that run them, the brokers who bring business, and the members who provide the capital. This is where insurance is actually written.
- The Corporation of Lloyd's: the Society's staff organisation. It supervises the market, holds the licences that let syndicates write business in more than 70 countries, and protects the Central Fund. In Lloyd's own words it is "not itself an insurer."
That split explains most of what is distinctive about Lloyd's. Because the insurers are separate businesses competing under one roof, a broker can shop a risk across dozens of specialists in a single building. Because they share one brand, one licence network and one central fund, a policyholder in Texas or Singapore has the same central backstop behind the policy whichever syndicate signed it.
Lloyd's is regulated in the UK by both the Prudential Regulation Authority and the Financial Conduct Authority, and on its own figures its market is rated A+ by AM Best and AA- by Fitch, KBRA and S&P Global. Those ratings apply to the market as a whole, which is one reason a small syndicate can sell cover that a small standalone insurer could not.
How Lloyd's of London Works: From Broker to Syndicate
Most business reaches Lloyd's through a broker. Lloyd's describes itself as "a broker market," and much of the negotiating still happens face to face in its underwriting room in London. The sequence for a large commercial risk looks like this:
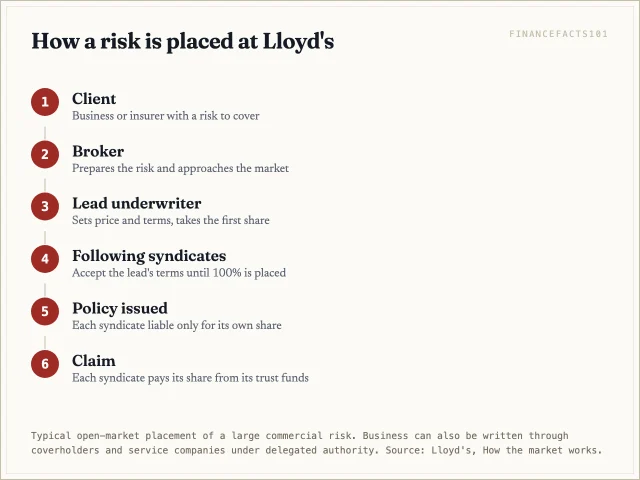
The key idea is the subscription market. A very large risk is rarely taken by one syndicate alone. The broker takes it to a lead underwriter, who sets the price and terms and takes a share, say 15%. The broker then collects other syndicates, which "follow" the lead's terms and take their own shares until 100% is covered. Each syndicate is liable only for its own share, which lets the market cover risks worth billions without any single balance sheet carrying all of it. Lloyd's explains that much of its capital is provided "on a subscription basis — where Lloyd's underwriters join together as syndicates and where syndicates join together to underwrite risks and programmes."
Not everything goes through the room. Managing agents can authorise coverholders, local businesses, many of them outside the UK, that sign policies on a syndicate's behalf within agreed limits, and service companies, which are owned by a managing agent and write contracts for its syndicate. This is how an American restaurant owner or a homeowner in coastal Florida can end up with a Lloyd's policy without anyone flying to London: a local agent places it with a coverholder that has authority from Lloyd's syndicates.
When a claim comes in, each syndicate that took a share pays its share, and the syndicate's own underwriters and claims staff handle it, usually with the broker acting for the client.
The Structure of the Lloyd's Market: Who Does What
The market has more moving parts than an ordinary insurer, but each has one job. The counts below are Lloyd's own, at December 31, 2025.

- Syndicates are the insurers in practice. A syndicate is formed by one or more members joining together to provide capital and accept risks. Technically each is set up for one year at a time, but members can carry on from year to year, so most operate like permanent businesses, each with its own business plan, appetite for risk and reinsurance.
- Managing agents run syndicates: they employ the underwriters, price the risks, buy reinsurance and handle claims. One managing agent may run several syndicates.
- Members supply the capital. They can be companies, including many of the world's largest insurance groups, or individuals. Corporate groups provide most of the capital.
- Members' agents advise individual members and help them choose syndicates.
- Brokers represent clients and bring risks to the market. Lloyd's registered brokers numbered 401 at the end of 2025.
- Coverholders and service companies give local access to Lloyd's around the world.
- The Corporation supervises all of the above, sets the rules and runs the central fund.
The Chain of Security: Who Pays If a Syndicate Can't
A Lloyd's policy is backed by three layers of money, which Lloyd's calls the Chain of Security. Its 2025 annual report puts the whole chain at "more than $160 billion deep."
- Syndicate assets (premium trust funds). Every premium a syndicate receives is held in trust by its managing agent and is the first source for paying claims. No profit can be released to members until the syndicate's liabilities are provided for.
- Funds at Lloyd's. Each member must post capital to back its share of underwriting. Managing agents calculate each syndicate's Solvency Capital Requirement at a 99.5% confidence level, over the full life of its liabilities rather than just 12 months; Lloyd's then adds a 35% uplift. A member's capital is held in trust for its policyholders and is not available for other members' debts.
- Central assets, including the Central Fund. If a member cannot pay, the Council of Lloyd's can use central assets, at its discretion, to meet any valid claim. This shared layer is a large part of why the rating agencies rate the market as a whole rather than syndicate by syndicate.
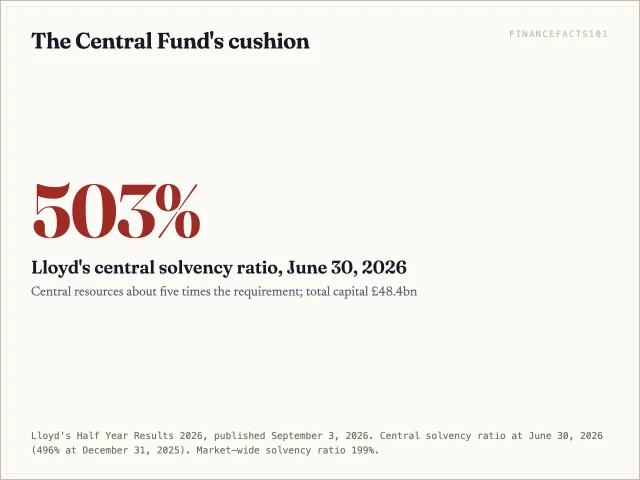
How strong is it now? Lloyd's reported a central solvency ratio of 503% at June 30, 2026, meaning central resources were about five times the regulatory requirement, and a market-wide solvency ratio of 199%. Total capital, reserves and subordinated loan notes stood at £48.4 billion.
What Lloyd's Insures
"Lloyd's of London insurance" is mostly commercial and specialty cover, with a large reinsurance book on top. Its 2025 annual report splits gross written premium into six lines of business:
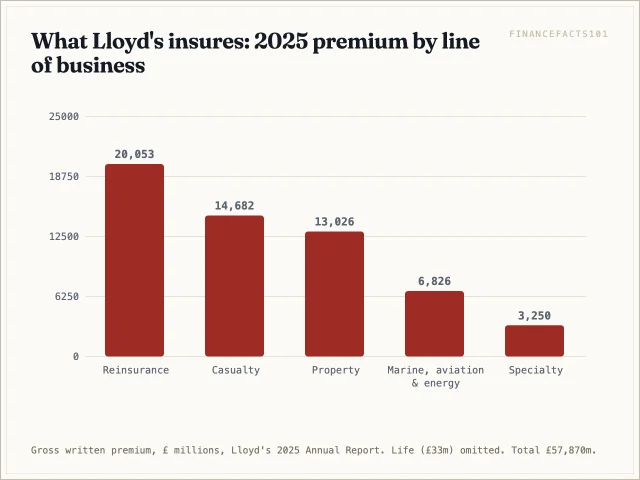
- Reinsurance (£20.1bn): insurance for insurers, led by property catastrophe excess of loss, the cover that pays when a hurricane or earthquake produces losses above an agreed level.
- Casualty (£14.7bn): long-tail general liability, financial and professional lines, workers' compensation, medical malpractice, accident and health, and cyber.
- Property (£13.0bn): a broad range of risks worldwide, mostly excess and surplus lines business and much of it written through coverholders.
- Marine, aviation and energy (£6.8bn): marine hull and cargo, aviation, and onshore and offshore energy. Marine is where Lloyd's started.
- Specialty (£3.3bn): mainly political risk and credit business, such as contract frustration, trade credit and political risk cover.
- Life (£33m): a sliver.
Individuals can buy Lloyd's cover too, usually without knowing it: a specialist home, classic-car, jewellery or event policy arranged by a local agent through a coverholder. The Lloyd's name on the policy tells you which syndicates are liable and for what share.
Gross written premium rose from £39.2bn in 2021 to £57.9bn in 2025. In 2025 Lloyd's credited 10.3% volume growth from new and existing syndicates, partly offset by a stronger pound and by prices that fell 3.7%; in the first half of 2026 prices fell a further 6.7% as competition increased.
Lloyd's of London in the United States
Lloyd's has written business in the United States for more than a century, and much of it is surplus lines insurance, meaning cover from insurers that are not licensed ("admitted") in the buyer's state, used for risks local insurers will not take. Lloyd's calls itself "one of the largest surplus lines insurers in the US." The NAIC describes the US surplus lines market as "U.S. domiciled insurers, Lloyd's syndicates, and non-U.S. insurers that have been admitted to the NAIC Quarterly Listing of Alien Insurers," and puts its size at $131 billion of direct premiums written in 2024.
What that means for you as a US buyer:
- You buy through a licensed surplus lines broker, not directly. Lloyd's lists the state databases where you can check a broker's licence.
- State guaranty funds do not apply. The NAIC states that the protection of a state guaranty fund is "not available to the surplus lines market." Your protection is the Lloyd's chain of security, including trust funds held in the US "as security for US policyholders."
- There may be a federal excise tax. Premiums paid to a foreign insurer are subject to the federal excise tax reported on IRS Form 720 as IRS No. 30: 4 cents per dollar on casualty insurance and indemnity bonds, 1 cent per dollar on life, sickness and accident policies and on reinsurance. The instructions put the duty on whoever pays the premium to the foreign insurer or a foreign broker; if that person does not pay, the one who issued or sold the policy, or the insured, must. Foreign insurers claiming a tax-treaty exemption must disclose it.
- Surplus lines premium tax still applies. The broker remits it to the policyholder's "home state," per the NAIC.
Reinsurance between the two countries has its own treaty. The U.S.-UK Covered Agreement, signed on December 18, 2018 and in force since December 31, 2020, addresses the same topics as the U.S.-EU Covered Agreement: group supervision, reinsurance supervision including collateral and local-presence requirements, and the exchange of information between supervisors.
Lloyd's of London Members: Names, Companies and How People Invest
Members are the people and companies whose capital backs the syndicates. Lloyd's lists three types:
- Corporate members, companies formed only to underwrite at Lloyd's, including limited companies, LLPs and Scottish limited partnerships.
- Qualifying corporate members, which operate without a members' agent.
- Individual members, historically called Names, "whose exposure to the insurance risks they underwrite is unlimited."
Members underwrite on a several basis: each is liable only for its own share and not for other members' losses. Lloyd's also counts around 2,500 third-party capital providers who back members indirectly.
You cannot buy shares in Lloyd's itself; the Society is not a listed company. The routes in are:
- Become a member. Lloyd's tells prospective members to contact a members' agent first. Individual membership carries unlimited personal liability for your share; corporate vehicles such as LLPs and Scottish limited partnerships are the limited-liability alternative.
- Invest through an insurance-linked securities vehicle. Lloyd's sponsored London Bridge 2 PCC, approved by UK regulators in August 2022, whose cells can provide capital to back Lloyd's underwriting.
- Buy shares in listed insurance groups that own managing agents and corporate members. That is an ordinary stock investment in a company, not membership of Lloyd's.
Lloyd's own investor pages say they are not soliciting membership or investment, and it refers would-be capital providers to managing agents and members' agents. For most readers, Lloyd's matters as a place to buy insurance, not as an investment.
A Short History of Lloyd's
Lloyd's began, by its own account, in Edward Lloyd's coffee shop by the Thames in the 1680s, where merchants, shipowners and underwriters met to share shipping news and insure voyages; an Insurance Journal history dates the coffeehouse to 1688. Edward Lloyd was never an insurer himself. He provided the place where others did business, which is still the model.
For most of its history the capital came from wealthy individual Names who pledged everything they owned. That model broke at the end of the 1980s and in the early 1990s, when asbestos and related claims arrived on policies written over the previous 40 years or more. Many Names lost heavily and some sued. Lloyd's responded with changes that remade the market:
- 1994: corporate capital was admitted for the first time; companies now provide most of the market's capital.
- 1996: under a "Reconstruction and Renewal" plan, Lloyd's created Equitas, a run-off company, to take on the old liabilities.
- End of 2001: Lloyd's stopped regulating itself and came under the UK Financial Services Authority. The FSA was later replaced, and today the PRA and the FCA regulate Lloyd's.
Brexit brought one more structural change. Lloyd's now requires insurance risks located in the European Economic Area to be written by Lloyd's Insurance Company S.A. ("Lloyd's Europe") in Brussels, which is regulated by the National Bank of Belgium, rather than by the London syndicates.
Lloyd's vs an Ordinary Insurance Company
The table sums up the differences for a policyholder.
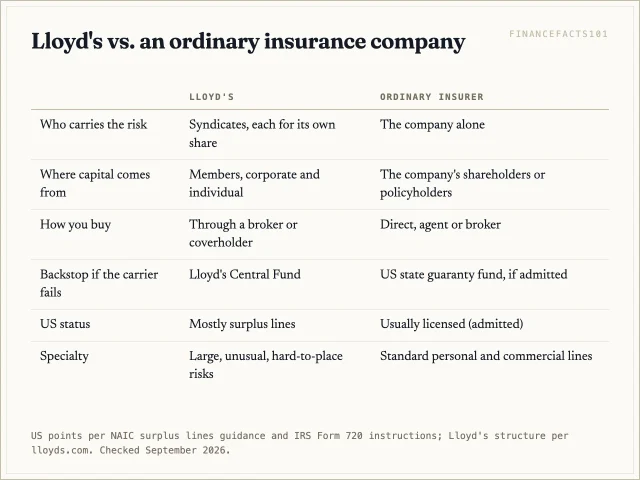
The practical upshot: a Lloyd's policy is often the answer when a risk is too large, too unusual or too recent for a standard insurer, from an offshore energy project to a property in a catastrophe-prone area. The price of that flexibility, for US buyers, is buying through the surplus lines system without a state guaranty fund. The legal basis of any claim is the same as with any insurer: the policyholder needs an insurable interest in what is covered. London's other historic markets work on a similar "venue, not principal" idea; see the London Stock Exchange and the London Metal Exchange.
FAQ
Is Lloyd's of London an insurance company?
No. Lloyd's is a marketplace. The insurance is written by syndicates run by managing agents and backed by members' capital. The Corporation of Lloyd's supervises the market and manages the Central Fund, and it describes itself as "not itself an insurer."
Can I buy insurance directly from Lloyd's of London?
Not directly. You buy through a broker, or through a local agent who places the risk with a Lloyd's coverholder. In the United States that usually means a licensed surplus lines broker.
Who are the members of Lloyd's of London?
Corporate members, which provide most of the capital and include many large insurance groups, and individual members, the traditional "Names," who carry unlimited liability for their share. Around 2,500 third-party capital providers also back members.
Is Lloyd's of London safe?
Its rating agencies think so: A+ from AM Best and AA- from Fitch, KBRA and S&P Global. Claims are backed by premium trust funds, members' capital and a Central Fund. The central solvency ratio was 503% at June 30, 2026. US buyers should note that state guaranty funds do not cover surplus lines policies.
Sources
- Lloyd's, Full Year Results 2025 press release (March 19, 2026) — £57.9bn gross written premium, 87.6% combined ratio, £10.6bn profit, ratings
- Lloyd's, Half Year Results 2026 press release (September 3, 2026) — £34.7bn GWP, 90.8% combined ratio, 503% central solvency, £48.4bn capital, price change (6.7)%
- Lloyd's, 2025 Annual Report — premium by line of business, five-year summary, chain of security "more than $160 billion deep"
- Lloyd's, How the market works — counts of syndicates, managing agents, brokers, coverholders and service companies at December 31, 2025
- Lloyd's, Our market, Governance, Capital structure, What is a member?, Invest with Lloyd's, History, Lloyd's in Belgium, United States
- National Association of Insurance Commissioners, Surplus lines — market definition, $131 billion (2024), no guaranty fund protection
- Internal Revenue Service, Instructions for Form 720 and Form 720 — foreign insurance excise tax, IRS No. 30
- U.S. Department of the Treasury, Federal Insurance Office, U.S.-UK Covered Agreement and U.S.-EU Covered Agreement — the three areas the agreements address
- Insurance Journal, "Lloyd's of London Finds its 21st Century Form" (September 5, 2005) — 1688 coffeehouse, 1994 corporate capital, 1996 Equitas, FSA supervision from end of 2001
 Next entry · No. 2,942Understanding Mutual Fund Loads: Front-End vs. Back-End
See also
-
 No. 3,619
13 Apr 2025
17 min
Understanding Occurrence Policies: Long-Term Protection against Financial Loss
Insurance
-
 No. 2,425
05 Jan 2025
21 min
The Innovative World of Insurtech: Transforming the Insurance Industry with Technology
Insurance
-
 No. 2,419
04 Jan 2025
23 min
Understanding Insurable Interest: Protecting Against Financial Loss
Insurance
-
 No. 5,610
23 Sep 2025
17 min
Understanding Warehouse Lending: An Essential Financing Tool for Mortgage Lenders
Business Finance
-
 No. 4,828
20 Jul 2025
19 min
Understanding Syndicates: Types, Risks, and Role in Financial Services
Business Finance
-
 No. 4,162
27 May 2025
20 min
Understanding Put Options: The Essentials for Institutional Investors
Business Finance