Medallion Signature Guarantees: What They Are, How They Work
A medallion signature guarantee is a bank or broker stamp that lets a transfer agent move shares. Often free; coverage runs from $100,000 into the millions.
A medallion signature guarantee — usually just called a medallion stamp — is a stamp from a participating bank, credit union or brokerage that certifies your signature on a securities transfer is genuine and that you have the authority to sign it. Transfer agents — the firms that keep a company's shareholder records — require one before they will sell, re-register or move shares out of your name, and the institution that stamps your form accepts financial liability if the signature turns out to be forged. You get one from a bank, credit union or broker where you already have an account, usually free.
That liability is the reason the process feels strict, and it explains almost every rule below: who can stamp, who they will stamp for, how much a single stamp can cover, and why a notary will not do. This page covers what the medallion stamp is, when you need one, where to get a signature guarantee at local banks and credit unions, what to bring, and what to do when nobody will give you one. It is general information as of September 2026; your transfer agent's written requirements govern your transaction.
What Is a Medallion Signature Guarantee?
A medallion signature guarantee is a promise, not just a verification. When an authorized officer stamps and signs your transfer form, the institution warrants three things under the Uniform Commercial Code's section 8-306: that the signature is genuine, that the signer was the appropriate person to sign, and that the signer had legal capacity to sign. If any of that is wrong, the guarantor "is liable to the person for loss resulting from their breach." In practice that means the bank or broker pays if it stamped a forger's signature and your shares were stolen.
The SEC's investor education office puts the purpose plainly: the program "protects you by making it harder for people to steal your securities by forging your signature," and transfer agents "insist on medallion signature guarantees because they limit their liability and losses if a signature turns out to be forged," per its medallion signature guarantee explainer.
The federal rule behind it is SEC Rule 17Ad-15. It defines a guarantee as a guarantee of the signature of the person endorsing a certificated security or originating an instruction to transfer ownership of a security — so it applies to book-entry shares as well as paper certificates. It lists who may be an eligible guarantor (banks — including the national banks supervised by the Office of the Comptroller of the Currency — brokers and dealers, credit unions, national securities exchanges and clearing agencies, and savings associations) and lets a transfer agent reject any guarantor that is not a member of a signature guarantee program. That clause is why the "medallion" matters: an ordinary bank officer's stamp reading "signature guaranteed" is no longer accepted by most transfer agents.
The Three Medallion Programs
Only institutions enrolled in one of three programs can issue a medallion signature guarantee:
- Securities Transfer Agents Medallion Program (STAMP) — the big one, with more than 7,000 U.S. and Canadian participants, including most banks and credit unions that offer the service.
- Stock Exchanges Medallion Program (SEMP) — regional stock exchange member firms, clearing firms and trust companies.
- New York Stock Exchange Medallion Signature Program (MSP) — NYSE member broker-dealers.
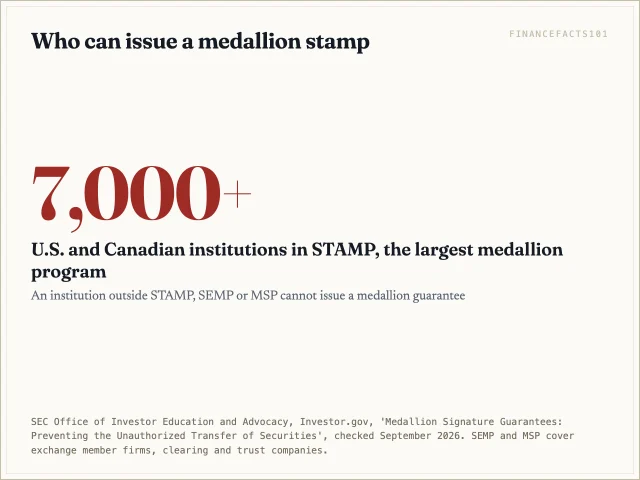
Guarantees issued under the programs are covered by surety bonds in various amounts, which is what gives the transfer agent someone to collect from if a guarantee proves false. According to the SEC's page on transferring assets, Kemark Financial Services administers STAMP and SEMP, and a transfer agent can refuse a guarantee from an institution that does not participate or that it does not recognize.
What a Medallion Stamp Looks Like — and What the Prefix Letter Means
A medallion stamp is an imprint that identifies the guaranteeing institution and the program, and carries a unique identification number that starts with a letter. The current STAMP version, STAMP2000, prints in high-security green ink surrounded by barcodes, and transfer agents authenticate it with a dedicated STAMP2000 document reader — which is why a photocopy or scan will not do. The authorized officer signs with the imprint, and the transfer agent can check that officer against the institution's list of authorized signers.
The letter at the front of the number is the part most people miss. It shows the maximum value the stamp covers — but we found no official schedule from the medallion programs or the SEC. The table below is one transfer agent's published schedule, from Colonial Stock Transfer. Other sources differ at the top: PNC gives example limits "up to $14,000,000," and a UK medallion provider lists a Z prefix covering up to $14 million for Securities Transfer Association members only. Colonial itself notes that STA-member transfer agents carry a further $4 million of insurance against stolen or counterfeit stamps, which may explain the gap. Your guarantor can confirm what its own stamp covers.
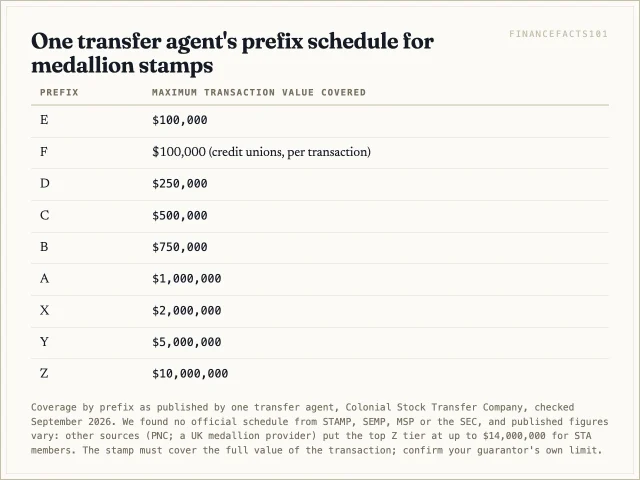
The stamp has to cover the full value of what you are moving. Transfer agent Colonial Stock Transfer requires the guarantee to cover the full transaction amount, and one fund family's prospectus spells out the consequence: "If the surety bond amount is not sufficient to cover the requested transaction(s), the Medallion Signature Guarantee will be rejected." It is also the likely source of the claim, repeated on older pages including an earlier version of this one, that a medallion guarantee can cost $100,000 or more: figures of that size are coverage limits, not fees.
The coverage level belongs to the institution, not to you. A branch whose stamp carries a low prefix simply cannot guarantee a large transfer, and some institutions set their own ceiling below their prefix. The Digital Federal Credit Union, for one, limits its members' guarantees to "$50,000 or less."
When You Need a Medallion Signature Guarantee
The trigger is always the same: someone other than you has to rely on your signature to move securities registered in your name, and there is no brokerage login to confirm it. Common situations:
- Selling or transferring paper stock certificates. You sign the certificate or a separate stock power, and the signature needs a medallion.
- Inherited shares. An executor or beneficiary re-registering a deceased owner's shares, usually with a death certificate, letters testamentary and an affidavit of domicile.
- Gifts. Moving shares from your name into a child's or another person's name.
- Direct-registered (DRS) shares held at a transfer agent in your name, when ownership changes or the shares are sold through the agent.
- Mutual fund requests outside the normal pattern. One fund family's SEC-filed prospectus says a medallion "may be required" when redemption proceeds go to a third party or to a bank not already on the account, for redemptions of $100,000 or more by check, and for share transfers — and adds that "a notary public stamp or seal is not acceptable." Other fund companies set their own thresholds.
- Changing account registration, such as retitling shares into a trust or removing a name after divorce.
You usually do not need one when your shares already sit in a brokerage account in "street name." In a broker-to-broker transfer, the firms handle the move between themselves and the signature risk sits with them. The SEC notes that holding securities in street name is "one way to avoid having to get your signature guaranteed."
Signature Guarantees at Local Banks and Credit Unions
The SEC's advice is to go where you already bank: "the best source of a medallion signature guarantee is a bank, savings and loan association, brokerage firm, or credit union with which you do business," and if you are not a customer of a participating institution, "it is likely the financial institution will not guarantee your signature." That is the honest answer to anyone searching for signature guarantees at local banks: your own community bank or credit union is the best first call, and a bank where you have no account will usually say no.
Policies differ sharply by institution, so call before you go. Two published examples, as of September 2026:
- Bank of America offers the stamp free, but only to Private Bank or Merrill investment clients of at least six months, in person, by appointment, with all owners present. It asks for government photo ID and account statements dated within one year, and it will not guarantee a transfer of assets out of a Bank of America or Merrill account. It says processing typically takes two business days and up to five for complex cases, per its medallion signature guarantee page.
- Digital Federal Credit Union offers it free to members at every branch, but not on the spot: staff review your documents first and, if approved, call you back to return for the signing. The document must be unsigned when you bring it, and guarantees are capped at $50,000.
Not every branch has an authorized officer on site; where one is missing, documents may be sent for off-site review, which adds days. If your usual bank refuses, try your brokerage (especially if the shares are moving to it) and then the transfer agent itself. The SEC says that if you have been unable to obtain a medallion guarantee, you should contact the transfer agent or issuer for help.
How to Get a Medallion Signature Guarantee, Step by Step
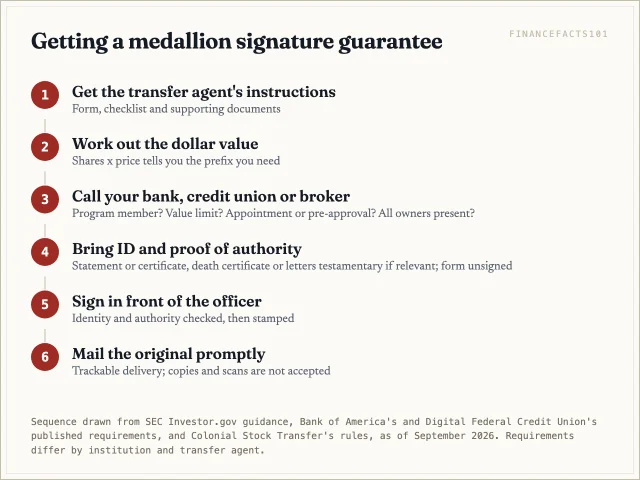
- Get the transfer agent's instructions first. The company's investor relations page names its transfer agent. Download the agent's transfer or re-registration form and its checklist of supporting documents.
- Work out the dollar value. Multiply the shares by the current price. That tells you which prefix you need, and some institutions will ask for it.
- Call your bank, credit union or broker. Ask whether they are in a medallion program, whether there is a value limit, whether you need an appointment, and whether every owner must attend.
- Bring everything, signed nothing. Photo ID for every signer, a recent statement or the certificate itself, the unsigned transfer form, and any legal documents that prove authority — a death certificate, letters testamentary, trust pages or power of attorney.
- Sign in front of the officer. They verify your identity and authority, watch you sign, then apply and sign the stamp.
- Send originals promptly. Transfer agents generally want the original stamped document; mail it with the rest of the packet, by a trackable method.
Worked example: an inherited position
Say an executor needs to re-register 2,400 shares that closed at $140 — a $336,000 transfer. Under the schedule above, a "D" prefix stamp covers up to $250,000, so it would be rejected; the executor needs at least a "C" stamp, good to $500,000. A credit union capped at $50,000 cannot help at all. The practical route is a bank or brokerage where the estate or executor has an account and whose stamp carries a C prefix or higher — and asking that question on the first phone call saves a wasted trip.
The same transfer carries a tax point worth knowing. Under IRS Publication 551, the basis of inherited property is generally its fair market value on the date of death, not what the original owner paid. That is what heirs should record, and it usually shrinks the taxable gain if they sell — the mechanics are in our guide to capital gains tax on stocks, and the capital gains tax calculator runs the numbers.
Medallion Guarantee vs. Notary vs. Other Stamps
People confuse these constantly, and the difference is liability.
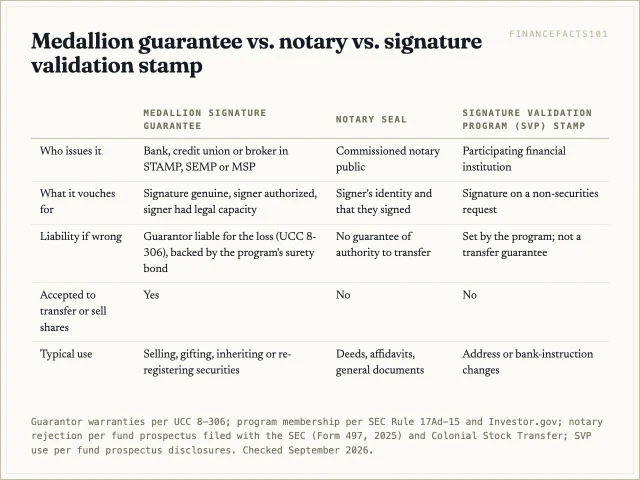
A notary public confirms who you are and that you signed; the notary does not promise that you had the right to transfer the shares and does not pay if you did not. That is why transfer agents and fund companies reject notarized forms for securities transfers. The Signature Validation Program (SVP) is a separate stamp that some transfer agents accept for non-securities changes — updating an address or banking instructions — but not for transferring ownership.
Cost, Timing and How Long a Medallion Stamp Is Good For
Cost. The SEC notes that guarantor firms can charge a fee but "often don't," offering the stamp as a customer service. Where fees exist they are modest — PNC describes $10 to $50 at institutions for non-account holders and $50 to $100 through third-party services. Treat any quote far above that with suspicion.
Timing. Same day if the branch has an authorized officer and your paperwork is complete; two to five business days when documents go for review.
Validity. No federal rule sets an expiry date. A stamp guarantees one signature on one document for one transaction, and it cannot be reused or moved to a new form. Because transfer agents check that nothing was altered after stamping and some question stale guarantees, get the stamp when the packet is otherwise ready to mail — not weeks ahead.
When You Can't Get One — and Ways to Avoid Needing One
If every institution says no — you have no account relationship, the value is above anyone's limit, or you live abroad — work through these in order:
- Open an account first. A brokerage account in your name, opened to receive the shares, often solves both the relationship problem and the stamp itself.
- Ask about overseas branches. The SEC notes investors abroad may get a stamp from an overseas branch of a U.S. or Canadian bank, broker or credit union they do business with.
- Call the transfer agent. The SEC's own advice is to contact the transfer agent or issuer for help if you cannot obtain a guarantee; ask what it will accept in your specific situation, and get the answer in writing.
- Stop the problem recurring. Move paper certificates and DRS positions into a brokerage account in street name. The SEC's bulletin on holding your securities lays out the trade-offs, including that lost physical certificates are costly to replace. Transfer-on-death registration also lets securities pass to a named beneficiary without probate; the beneficiary still has to send the agent a death certificate and a re-registration application.
FAQ
How long is a medallion signature guarantee good for?
There is no federal expiry date. A medallion stamp covers the specific document and transaction it was applied to, and it cannot be reused. Because transfer agents may question an old or altered guarantee, get it when your transfer packet is complete and ready to send.
Can a notary do a medallion signature guarantee?
No. A notary verifies identity but does not guarantee authority or accept liability for a forged transfer, and transfer agents and fund companies reject notarized signatures for securities transfers. Only a bank, credit union, broker or other eligible institution enrolled in STAMP, SEMP or MSP can issue a medallion stamp.
Can I get a medallion signature guarantee without an account?
Rarely. The SEC says a participating institution is unlikely to guarantee the signature of someone who is not a customer. The practical fixes are to open an account at a bank or brokerage (often the one receiving the shares), ask the transfer agent for help, or, as a last resort, use a paid third-party service after checking that the transfer agent will accept its stamp.
What is the difference between a medallion stamp and a signature guarantee?
A medallion stamp is a signature guarantee issued under one of the three recognized medallion programs, with a prefix showing its surety coverage. An older "signature guaranteed" stamp from an institution outside those programs can be rejected under SEC Rule 17Ad-15, so in practice transfer agents treat "signature guarantee" as meaning a medallion.
How much does a medallion signature guarantee cost?
Usually nothing for existing customers. Some institutions charge non-customers roughly $10 to $50, and third-party services commonly charge $50 to $100. The dollar figures in the hundreds of thousands that circulate online are coverage limits, not fees.
Sources
- SEC, Investor.gov, Medallion Signature Guarantees: Preventing the Unauthorized Transfer of Securities — the three programs, 7,000+ STAMP participants, where to get one, overseas investors
- SEC, Investor.gov, Transferring assets — street name avoids the requirement, fees "often" waived, Kemark administers STAMP and SEMP, TOD registration
- SEC, Investor.gov, Investor Bulletin: Holding Your Securities (July 12, 2023)
- SEC Rule 17Ad-15, 17 CFR 240.17Ad-15, Signature guarantees — eligible guarantor institutions and signature guarantee programs
- New York Life Investments Funds, prospectus supplement filed with the SEC (Form 497, 2025) — when a fund requires a medallion; notary not acceptable
- IRS, Publication 551, Basis of Assets — basis of inherited property
- Uniform Commercial Code, § 8-306, Effect of guaranteeing signature (Cornell LII)
- Colonial Stock Transfer, Medallion Signature Guarantees — one transfer agent's prefix coverage schedule, STAMP2000, full-amount rule, $4 million STA insurance
- Medallion Guarantee (UK), Medallion surety limits — Z prefix up to $14 million for STA members
- Bank of America, Medallion Signature Guarantee — eligibility, documents, timing
- Digital Federal Credit Union, Medallion Signature Guarantee — free to members, review before signing, $50,000 limit
- PNC, What is a Medallion Signature Guarantee and How Do You Get One? — typical non-customer fees; example coverage limits up to $14 million
 Next entry · No. 3,160Creating a Compelling Media Kit for Institutional Investors: A Comprehensive Guide
See also
-
 No. 3,641
15 Apr 2025
19 min
The Role, Power, and Functioning of the Office of the Comptroller of the Currency (OCC)
Business Finance
-
 No. 3,472
01 Apr 2025
20 min
Understanding Night Depositories: A Secure Option for Businesses Dealing Mainly in Cash and Checks
Business Finance
-
 No. 3,196
09 Mar 2025
18 min
The Middle Office: Bridging the Gap Between Front and Back Offices in Finance
Business Finance
-
 No. 3,139
04 Mar 2025
19 min
Understanding Mastercard: An In-Depth Look into the Global Payments Processing Giant
Business Finance
-
 No. 2,785
04 Feb 2025
18 min
Understanding Lead Banks: Role, Functions, and Significance in Finance and Investment
Business Finance
-
 No. 2,688
27 Jan 2025
17 min
Kenneth I. Chenault: The First Black Fortune 500 CEO
Business Finance