Value at Risk (VaR): Definition, Methodologies, Advantages and Limits
Value at risk (VaR) is the loss a portfolio should not exceed on 95% or 99% of days. The three methods, worked on $100,000 of S&P 500 data to Sept 2026.
Value at risk (VaR) is an estimate of the most a portfolio should lose over a set period, at a set level of confidence. A one-day 95% VaR of $1,670 on a $100,000 portfolio means that on 95 days out of 100 you should lose less than $1,670, and on the other 5 you should expect to lose more. It is a threshold, not a worst case.
That single number is why VaR became the standard language of market risk at banks, trading firms and fund managers. It is also why it misleads people who read it as "the most I can lose." This page gives the definition, how to read a VaR figure, the three methodologies (historical, variance-covariance and Monte Carlo), a worked example on real S&P 500 data through September 25, 2026, the role VaR plays in bank regulation and SEC disclosure, and its advantages and disadvantages.
What Is Value at Risk (VaR)?
In finance, "VaR" means value at risk. It answers one question: how bad can a normal bad day, week or month get? Every VaR figure has three parts:
- A loss amount, in dollars or as a percentage of the portfolio.
- A time horizon, such as one day or ten trading days.
- A confidence level, usually 95% or 99%.
Read together: "With 99% confidence, this portfolio will not lose more than $2.4 million over the next trading day." Turned around, the same sentence says a loss larger than $2.4 million should happen on about 1 day in 100. That is 2 or 3 days in a trading year of about 250 days.
Two confusions come up constantly with the "var meaning" searches. First, VaR is not variance, though the two are related: one common VaR method is built from the variance (or standard deviation) of returns. Second, in economics "VAR" in capitals usually means vector autoregression, a forecasting model with nothing to do with portfolio losses. On a trading desk or in a bank's annual report, VaR is value at risk.
VaR measures market risk, the risk of loss from moves in prices, interest rates, exchange rates and commodity prices. It does not by itself measure the chance that a borrower defaults or that a system fails. For those, see our overview of risk assessment in finance.
How to Read a VaR Number
Three details change what a VaR figure means, and you should look for all three before comparing two numbers.
Confidence level. A 99% VaR is always larger than a 95% VaR for the same portfolio, because it reaches further into the tail. Goldman Sachs, for example, reports VaR at a 95% confidence level over a one-day horizon in its quarterly Form 10-Q. The Federal Reserve's market risk capital rule uses 99%.
Horizon. A 10-day VaR is larger than a 1-day VaR. A common shortcut multiplies the one-day figure by the square root of the number of days, which assumes each day is independent of the last. Our $1,670 one-day example becomes about $5,281 over 10 days under that rule.
What it leaves out. VaR says how often a loss should exceed the threshold, not how large the excess will be. Two portfolios with the same VaR can have very different worst days. That gap is what expected shortfall, also called conditional value at risk, was designed to fill.
VaR Methodologies: Historical, Variance-Covariance and Monte Carlo
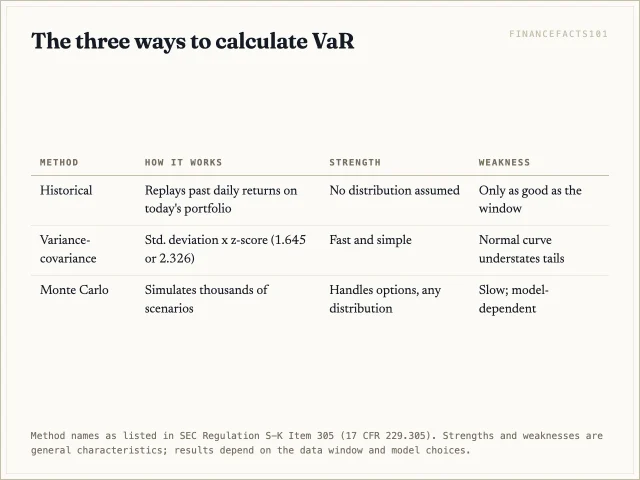
There are three standard ways to calculate VaR. The SEC's market risk disclosure rule names all three as model types a company should describe: "variance/covariance, historical simulation, or Monte Carlo simulation" (Regulation S-K Item 305).
Historical method
Take the portfolio you hold today and apply the actual daily returns from a past window, often one or two years. Sort the results from worst to best and read off the loss at the chosen percentile. With 500 days and 95% confidence, 5% of 500 is 25, so the VaR is the 25th-worst day. The method assumes nothing about the shape of returns, but it assumes the past window is a fair sample of the future.
Variance-covariance (parametric) method
Assume returns follow a normal distribution. Then VaR is a multiple of the standard deviation: 1.645 standard deviations for 95% confidence and 2.326 for 99% (one-tailed). For a multi-asset portfolio, the standard deviation comes from each asset's volatility and the correlations between them, which is where the name "variance-covariance" comes from. The formula is fast and simple. Its weakness is the normal assumption: real market returns have fatter tails, so the method tends to understate the 99% loss.
Monte Carlo simulation
Generate thousands of possible future paths for every risk factor, from a statistical model or by resampling history, and revalue the portfolio on each path. The VaR is the chosen percentile of the simulated results. Monte Carlo is the slowest method but the most flexible, and it copes well with options and other positions whose value does not move in a straight line with prices, which the parametric method handles poorly. The Federal Reserve's rule requires a bank's VaR model to capture "the nonlinear price characteristics of options positions."
Worked Example: VaR on $100,000 of the S&P 500
Here is a real calculation, not a hypothetical. The portfolio is $100,000 in an S&P 500 index fund, ignoring dividends and fees. The data are the 500 daily closing-price returns of the S&P 500 index from September 27, 2024 through September 25, 2026, taken from Cboe's published index history. Over that window the index rose from 5,745.37 to 7,743.41.
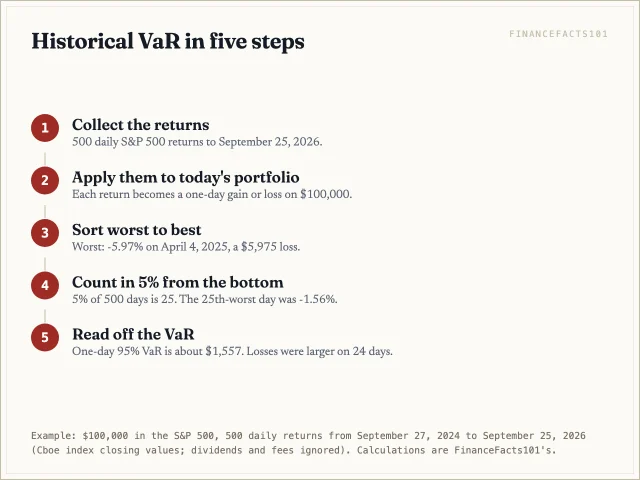
Historical 95%. The 25th-worst day of the 500 was November 20, 2025, a fall of 1.56%. The one-day 95% VaR is therefore about $1,557. Losses were larger on 24 days, just under 5%.
Historical 99%. The 5th-worst day was October 10, 2025, down 2.71%, so the one-day 99% VaR is about $2,711. The four days worse than that included April 3 and April 4, 2025, when the index fell 4.84% and 5.97%.
Parametric. The standard deviation of the 500 returns was 1.015% a day. Multiply by 1.645 and 2.326 and you get a 95% VaR of $1,670 and a 99% VaR of $2,361.
Monte Carlo. We resampled the same 500 returns to build 10,000 simulated 10-day paths. In that run the 10-day 95% VaR was 4.59% ($4,590) and the 99% VaR was 7.29% ($7,290). Repeating it with different random draws gave about 4.4% to 4.6% ($4,400 to $4,600) at 95% and about 6.9% to 7.3% at 99%, so treat the first run as the top of that range. The square-root-of-time shortcut applied to the parametric figure gives a higher 10-day 95% number, $5,281.
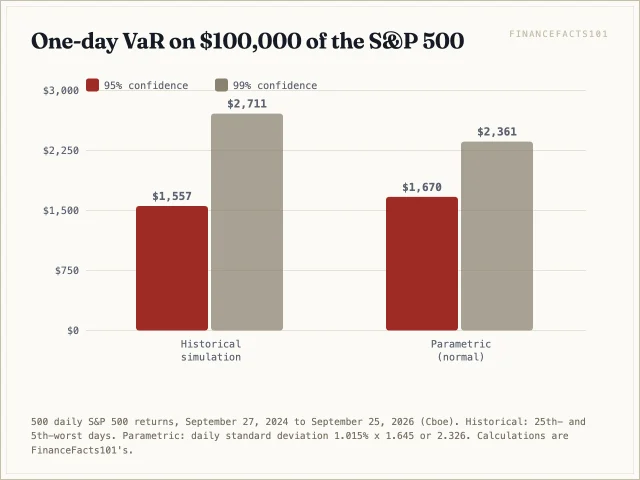
Compare the two methods and you see the normal assumption at work. At 95% the parametric figure is slightly higher than the historical one. At 99% it is about $350 lower, because the real distribution has more extreme days than a bell curve predicts. In the 500-day sample, 7 days fell by more than 2.326 standard deviations. A normal distribution would predict about 5.
A forward-looking variant uses implied volatility instead of history. The Cboe Volatility Index closed at 14.87 on September 25, 2026 (Cboe VIX history), which implies about 0.94% a day and a one-day 95% VaR near $1,541 on the same $100,000.
The Role of Value at Risk at Banks and Companies
Searches for "the role of value at risk" usually want to know what VaR is used for in practice. It has four main jobs.
Trading limits. Firms cap how much VaR each desk may run. A limit expressed in VaR works across bonds, stocks, currencies and commodities at once, which a limit in dollars of exposure cannot do.
Regulatory capital. The Federal Reserve's market risk rule applies to banks whose trading assets and liabilities reach $1 billion, or 10% of total assets. Under it, a bank's internal model must produce a daily VaR at "a one-tail, 99.0 percent confidence level," with a 10-business-day holding period and at least one year of data (12 CFR 217.205). The capital requirement is the greater of the previous day's VaR or the average of the last 60 business days' VaR multiplied by three (12 CFR 217.204). A separate "stressed VaR," run on the same model but with inputs from a continuous 12-month period of significant financial stress, is added on top.
Backtesting. Each quarter, the bank counts how many of the last 250 business days produced a trading loss larger than that day's one-day 99% VaR. Four or fewer exceptions keep the multiplier at 3.00. More exceptions raise it, up to 4.00 for ten or more, so a model that underestimates risk costs the bank capital.
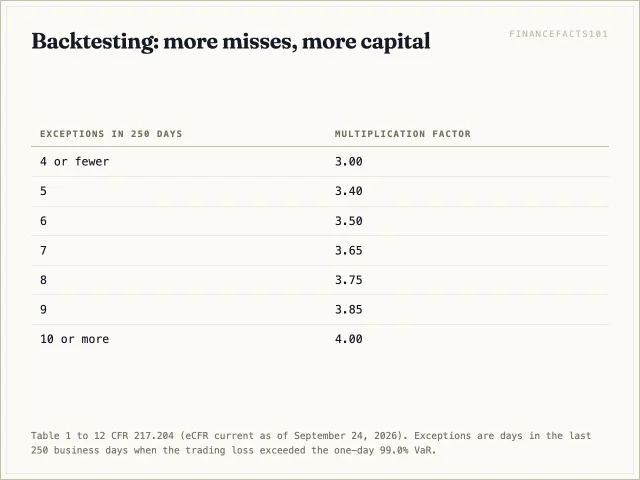
Our S&P 500 example gives a feel for this. Re-estimating the parametric 99% VaR each day from the prior 500 days and testing it on the last 250 trading days to September 25, 2026 produced 2 exceptions, October 10, 2025 and June 5, 2026. That would sit in the lowest-multiplier zone. The historical version produced none.
Public disclosure. Item 305 requires public companies, other than smaller reporting companies, to give quantitative market risk information in one of three formats, and VaR is one of them. A company choosing VaR must also report, for example, the average, high and low VaR for the period or how often actual losses exceeded it, and describe the model. Banks publish their VaR every quarter. Goldman Sachs reported average daily VaR of $120 million for the second quarter of 2026, up from $112 million in the first quarter, in its earnings release.
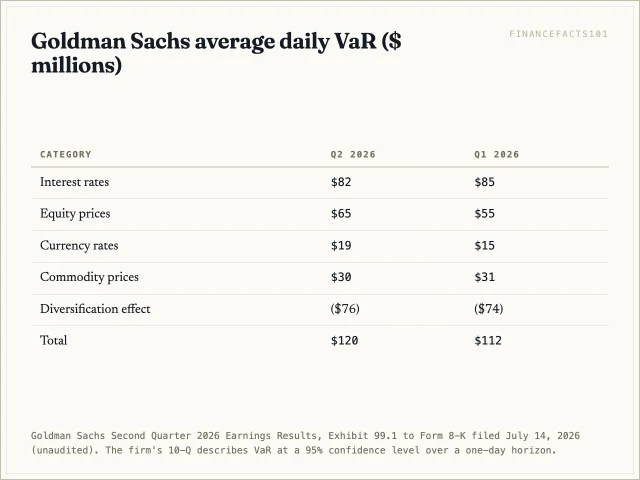
The "diversification effect" line is VaR's main selling point in action. Interest rate, equity, currency and commodity risk add up to $196 million measured separately, but they do not all lose on the same day, so the combined figure is $76 million lower.
Advantages of Value at Risk
VaR spread because it does several jobs that no single alternative does as well, and each advantage maps to one of the roles above.
- One number across asset classes. A board or regulator can compare a bond desk with a currency desk in the same unit.
- Probability built in. Unlike a simple "what if rates rise 1%" scenario, VaR ties a loss to how often it should occur.
- Testable. Because a 99% VaR should be breached on about 1% of days, you can count exceptions and check the model, as the Fed's backtesting rule does.
- Captures diversification. The correlation between positions lowers the total, rewarding genuinely offsetting risks.
- Flexible. It can be run for a single position, a desk or a whole firm, over any horizon.
None of these advantages says anything about how large a loss can get once the threshold is crossed. That is the core of the case against it.
Disadvantages of Value at Risk: What It Misses
It says nothing about the size of the tail. VaR marks where the bad 1% or 5% of days begin, not how bad they get. On April 2, 2025, a parametric 99% VaR estimated from the prior 500 days was 1.88%; the historical version was 2.12%. The next two days the S&P 500 fell 4.84% and 5.97%, roughly two and a half and three times the parametric estimate.
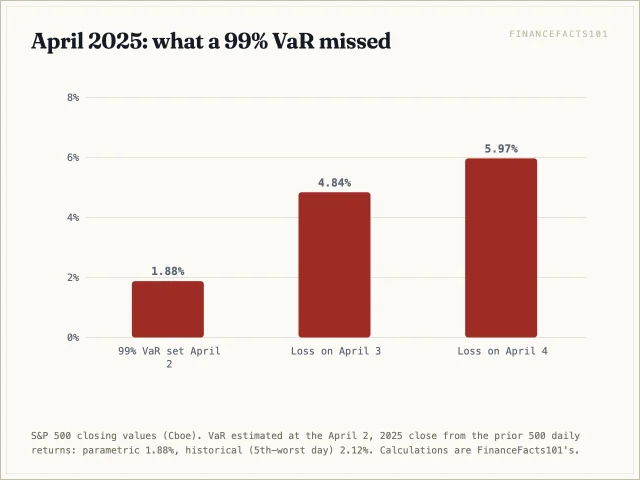
It depends on the window. Calm years produce low VaR, which invites larger positions just before volatility returns. A window that includes a crash produces high VaR for as long as the crash stays in the data.
It assumes you can exit. A 1-day or 10-day horizon assumes positions can be sold or hedged within that time. In a crisis, some cannot.
It can hide concentrated bets. A position that loses rarely but heavily, such as selling deep out-of-the-money options, can show a small VaR because its losses sit beyond the 99th percentile. For measures built to see those, see our entry on downside risk.
It does not always add up sensibly. In some cases the VaR of two combined portfolios can exceed the sum of their separate VaRs. That breaks the intuition that combining positions should not add risk.
Regulators have acted on these criticisms. On March 19, 2026, the Federal Reserve, FDIC and OCC proposed rules that would, among other changes, replace "the value-at-risk (VaR) based measure of market risk with an expected shortfall-based measure that better accounts for tail risk," according to the agencies' fact sheet. Comments were due June 18, 2026. As of October 9, 2026 the proposal had not been finalized and no final rule had been published in the Federal Register, so the VaR-based rule described above still applies.
VaR vs Standard Deviation and Expected Shortfall
VaR vs standard deviation. Standard deviation measures how widely returns scatter around the average, counting gains and losses alike. VaR looks only at the loss side and converts it into money at a chosen probability. Under the parametric method they are directly linked: VaR is standard deviation times a z-score times the portfolio value. Under the historical and Monte Carlo methods there is no fixed link, which is why they can capture fat tails that standard deviation misses.
VaR vs expected shortfall (CVaR). Expected shortfall asks the follow-up question VaR skips: when a loss is beyond the VaR, how large is it on average? In our example the one-day 95% VaR was $1,557, but the average of the 25 worst days was a 2.29% loss, or $2,288. The 99% expected shortfall, the average of the five worst days, was 3.99%, far above the 2.71% VaR. That is why the March 2026 proposal would move bank capital to expected shortfall.
For an individual investor, the practical lesson of VaR is modest but useful. A diversified stock index fund had a normal bad day of about 1.5% to 1.7% over the last two years, and a 1-in-100 day of about 2.4% to 2.7%. Yet on two consecutive days in April 2025 it lost 4.84% and then 5.97%. This page is general information, not investment advice.
FAQ
What is VaR in finance, in simple terms?
Value at risk is the loss amount that a portfolio should not exceed over a given period at a given confidence level. A one-day 99% VaR of $1 million means losses should exceed $1 million on only about 1 trading day in 100.
How is VaR calculated?
By one of three methods. The historical method replays past returns on today's portfolio and reads off a percentile. The variance-covariance method multiplies the portfolio's standard deviation by a z-score (1.645 for 95%, 2.326 for 99%). Monte Carlo simulation generates thousands of scenarios and takes the percentile of the simulated losses.
What is the difference between VaR and CVaR?
VaR is the threshold loss at a confidence level. CVaR, or expected shortfall, is the average loss on the days beyond that threshold, so it is always at least as large as VaR. In our S&P 500 example, the 95% VaR was 1.56% and the 95% expected shortfall 2.29%.
Why do banks use a 99% confidence level and 10 days?
Because the Federal Reserve's market risk capital rule, 12 CFR 217.205, requires a one-tail 99.0% confidence level and a 10-business-day holding period for the VaR-based measure. Banks may compute one-day VaR and convert it to 10 days if they can justify the method. Many banks report a 95% one-day VaR to investors, which is a different, smaller number.
Sources
- eCFR, 12 CFR 217.204, Measure for market risk and 12 CFR 217.205, VaR-based measure, current as of September 24, 2026: 99.0% one-tail, 10-business-day horizon, one-year observation period, multiplier of three, 60-day average, 250-day backtesting and Table 1 multiplication factors
- eCFR, 17 CFR 229.305, Regulation S-K Item 305, Quantitative and qualitative disclosures about market risk
- Federal Reserve, FDIC and OCC, Fact Sheet: Proposals to Modernize the Regulatory Capital Framework and press release, March 19, 2026; comment deadline June 18, 2026. No final rule appeared in the Board's or the FDIC's press releases or in the Federal Register through October 9, 2026.
- The Goldman Sachs Group, Inc., Second Quarter 2026 Earnings Results presentation, Exhibit 99.1 to Form 8-K filed July 14, 2026: Average Daily VaR table
- The Goldman Sachs Group, Inc., Form 10-Q for the quarter ended June 30, 2026, filed August 3, 2026: VaR confidence level and horizon
- Cboe Global Markets, S&P 500 index daily closing history and VIX historical data, through September 25, 2026. All example calculations are ours, from those closing values.
 Next entry · No. 5,428Understanding Variability in Finance: Measuring Risk and Return
See also
-
 No. 4,993
03 Aug 2025
17 min
Understanding Tombstones: The Role, Importance and Process of this Financial Advertisement
Business Finance
-
 No. 4,483
22 Jun 2025
18 min
Comprehensive Guide to Risk Assessment in Finance and Investment
Financial Education
-
 No. 4,356
12 Jun 2025
17 min
Rehypothecation: What It Means, How Brokers Use Client Assets, and the Risks
Business Finance
-
 No. 5,683
29 Sep 2025
22 min
Understanding the West African CFA Franc (XOF): The Shared Currency of Eight West African Nations
Finance Policy
-
 No. 5,522
16 Sep 2025
20 min
Understanding Volatility Swaps: A Pure Play on Asset Volatility
Finance Policy
-
 No. 5,437
08 Sep 2025
14 min
Variable-Rate Certificate of Deposit (CD): How Adjustable-Rate CDs Work
Finance Policy